Lenovo’s AI server backlog tops $50 billion as revenue surges 43%
Lenovo Group reported a 43% revenue increase to $26.9 billion and a 176% surge in adjusted net profit to $1.1 billion for the first quarter of fiscal 2026/27, driven by AI server demand. CFO Zheng Xiaoming revealed an AI-related order backlog exceeding $50 billion, all for AI servers. The company’s stock hit a record high, with market cap surpassing Meituan, Baidu, and JD.com. Lenovo aims for $100 billion in revenue this fiscal year and a long-term net margin of 5%.
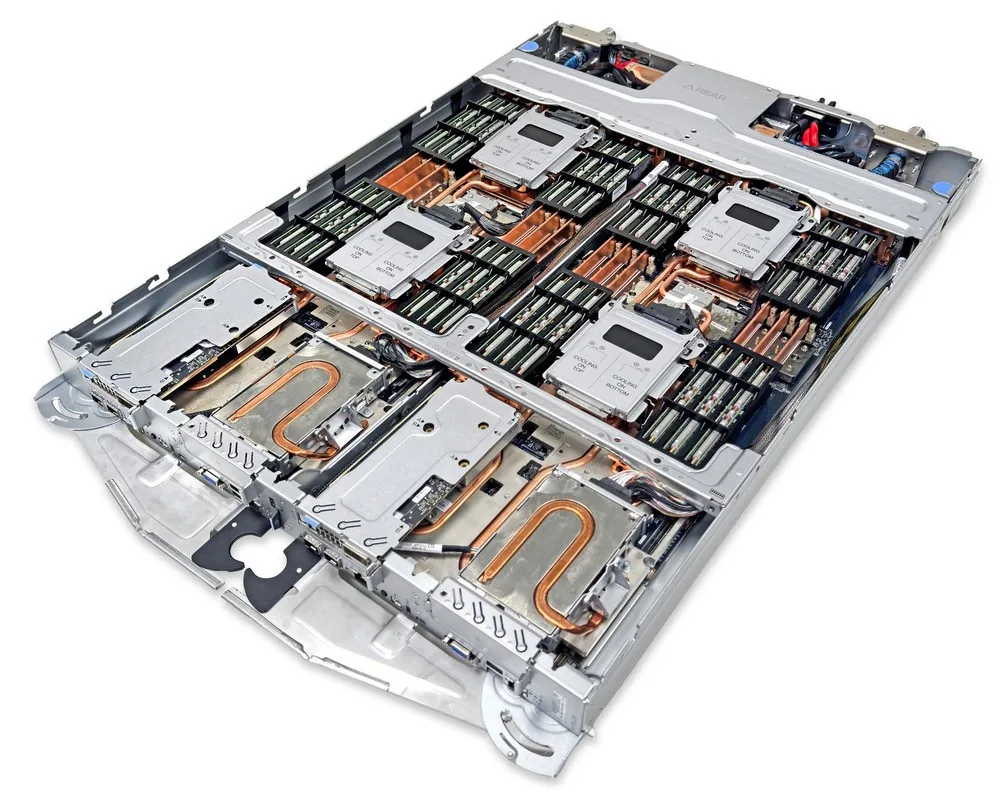 Illustration
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Reporting timeline
Lenovo's Market Cap Surpasses Meituan, Baidu, JD.com on $54 Billion AI Server Orders
This article analyzes Lenovo's dramatic market capitalization surge in 2026, during which it overtook Baidu, JD.com, and Meituan to reach over HKD 457.9 billion. The rally is attributed to a $54 billion AI server order backlog, a 176% year-on-year net profit increase to $1.075 billion, and a 43% revenue jump to $26.9 billion in the latest quarter. Morgan Stanley issued an 'overweight' rating with a HKD 46 target price. Lenovo CFO stated the company has been 'severely undervalued' by the market, citing a valuation gap versus Dell. The article argues that Lenovo's long-term strategy, including the 2014 acquisition of IBM's x86 server business and eight years of losses in that unit, positioned it to capitalize on the AI boom. However, it also notes risks: the $54 billion figure is an order backlog, not recognized revenue; the company holds $15.7 billion in chip inventory; and competition from Dell, Inspur, and Huawei is intense. The piece frames Lenovo's 'trade-industry-technology' model as finally validated in the AI era, contrasting its infrastructure role with Nvidia's high-margin chip business.
Read sourceLenovo's Undervaluation Tied to AI Infrastructure Shift, Analysts Say
A detailed analysis from a NetEase Finance article argues that Lenovo is significantly undervalued due to a market misperception of its role in the AI infrastructure buildout. The article, based on an AI investment summit, highlights a shift from buying AI hardware to building integrated systems, exemplified by the need for reinforced factory floors and high-power substations for 'supernode' production. Lenovo's ISG revenue surged 98% to 579 billion yuan, with AI server orders exceeding 360 billion yuan. Analysts and Lenovo's CFO, Zheng Xiaoming, project a path to 5-8% net profit margins through a mix of high-margin storage, services, and enterprise AI, contrasting with current low-margin cloud deals. The article argues Lenovo's valuation is roughly one-seventh of Dell's, despite comparable revenue and profit, due to its legacy PC label and low-margin manufacturing perception. It concludes that as Lenovo's order conversion and margin improvement materialize, a valuation framework shift could unlock significant upside, with a potential target of $100 billion in revenue and 5% net profit margin.
Lenovo's Undervaluation Tied to AI Infrastructure Shift, Analyst Says
A financial analysis article from NetEase Finance argues that Lenovo is undervalued, not just in stock price but in its strategic position within the AI infrastructure buildout. The piece, based on an AI investment summit, highlights a shift from buying AI hardware to building integrated systems, exemplified by 'super nodes' requiring heavy-duty factory floors and massive power. Lenovo's ISG business is cited with strong revenue growth (98% YoY) and a record operating margin of 9.1%. The analysis breaks down Lenovo's potential market cap into three drivers: revenue (driven by market share and a $360B order backlog), net profit margin (improving via a shift to higher-margin storage and services), and valuation multiple (currently a fraction of Dell's, with potential to re-rate). The article concludes that AI competition is now a 'systems' war involving power, land, and engineering, and that Lenovo's full-stack capabilities are not yet priced in by the market.
Show 2 older updatesHide older updates
Lenovo's AI Server Boom Drives Record Revenue, Stock Surge, and a Comeback Narrative
This article from Tencent Finance analyzes Lenovo's dramatic financial turnaround, driven by surging demand for AI servers and infrastructure. In August 2026, Lenovo reported quarterly revenue of $26.94 billion, up 43% year-over-year, and adjusted net profit of $1.075 billion, up 176%, far exceeding analyst expectations. The stock hit a record high of 34.08 Hong Kong dollars, rising 276% year-to-date. The core driver is the ISG (Infrastructure Solutions Group) segment, which saw revenue grow 98% to $8.5 billion, with operating margins at a record 9.1%. The article attributes this to massive AI capital expenditure by cloud giants, Lenovo's global manufacturing footprint (which became critical amid tariff wars), its 2014 acquisition of IBM's x86 server business, and its proprietary Neptune liquid cooling technology. CEO Yang Yuanqing is quoted forecasting that 70% of AI compute will shift from training to inference. The article also notes risks: a 4% net profit margin still below the 5-8% target, dependence on Nvidia chips, and the cyclical nature of AI capex. It frames Lenovo's transformation from a 'PC assembler' to an 'AI company' as a historic narrative shift.
Read sourceLenovo CFO Says Company Undervalued, Reveals $50 Billion AI Server Order Backlog
In a dialogue at the AI Investment Summit hosted by Sina Finance, Lenovo Group CFO Zheng Xiaoming stated the company is undervalued compared to Dell, with a valuation roughly one-seventh despite similar revenue and profit. He revealed that Lenovo's AI-related order backlog has grown to over $50 billion, all for AI servers. Zheng guided that Lenovo may achieve its $100 billion revenue target this fiscal year and aims for a long-term net margin of 5%, with value-added services above 8%. In the first quarter of fiscal year 2026/27, Lenovo's revenue rose 43% year-on-year to $26.9 billion, and adjusted net profit surged 176% to $1.1 billion. AI-related revenue grew 60% to $9.3 billion, accounting for 35% of total revenue. Zheng attributed the share price rise to business improvements and sees AI infrastructure as a long-term 'compute factory' construction cycle, with NVIDIA working on a $500 billion capital pool for neocloud construction. He also noted Lenovo's acquisition of a storage company in April to improve margins.