China’s 2026 private enterprise top 500: Fujian and Anhui rise as Hubei and Chongqing decline
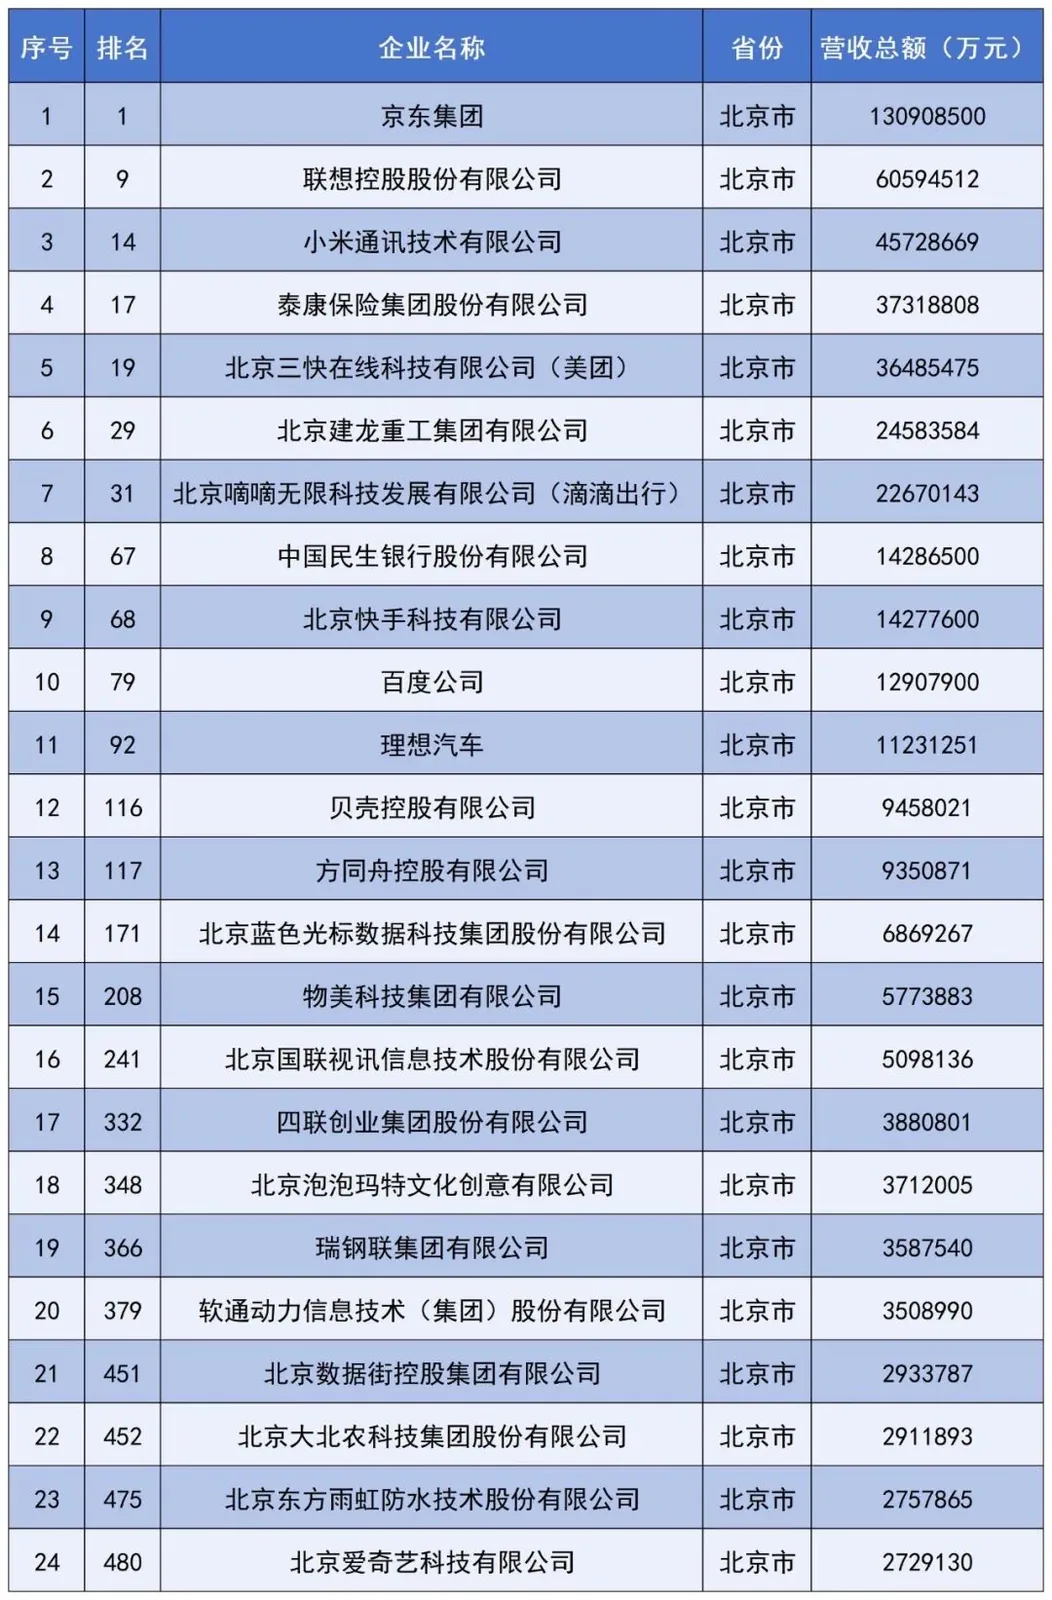
On September 22, the All-China Federation of Industry and Commerce released the 2026 China Top 500 Private Enterprises list, showing total revenue of 44.9 trillion yuan, nearly 30% of China’s 2025 GDP. Eastern coastal provinces dominate with 79% of firms and 85% of revenue. Zhejiang leads with 104 firms, followed by Jiangsu (90) and Guangdong (49). Over five years, Fujian and Anhui each added five firms, while Hubei lost seven and Chongqing lost five, reflecting a shift from real estate to new energy and technology.
 Reference image
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Reporting timeline
China's Top 500 Private Firms: Regional Shifts Reveal Winners and Losers in Economic Transition
An analysis of the 2026 China Top 500 Private Enterprises list, published by the National Federation of Industry and Commerce on September 22, reveals significant regional shifts over the past five years (2022-2026). Zhejiang, Jiangsu, Shandong, and Guangdong remain the top four provinces, accounting for over 60% of listed firms, though their individual counts have slightly declined or stabilized. The most notable gains occurred in Fujian and Anhui, each adding five listed firms, driven by distinct growth models: Anhui's hard-tech chain breakthroughs (solar, EVs, batteries, AI) and Fujian's diversified mix of manufacturing, consumer brands, and global trade. The biggest declines were in Hubei (down 7 firms) and Chongqing (down 5 firms), largely due to the exit of real estate-related companies. Shaanxi also shrank from 5 to 3 firms, losing its last billion-dollar private firm. The report attributes these shifts to a structural economic transition from traditional sectors like real estate and steel toward new energy, technology, and consumer services, with provincial winners and losers reflecting their ability to adapt.
Read sourceChina Private Enterprise Top 500: Zhejiang, Jiangsu, Guangdong Lead; Strategic Emerging Industries Reshape Regional Competitiveness
On September 22, the All-China Federation of Industry and Commerce released the '2026 China Private Enterprise Top 500' list, with total revenue of 44.9 trillion yuan, nearly 30% of China's 2025 GDP. The list reveals a stark regional divide: eastern coastal provinces account for 79% of the firms and 85% of total revenue. Zhejiang leads with 104 firms, followed by Jiangsu (90), Shandong, and Guangdong (49). The article, attributed to 21st Century Business Herald researcher Li Guo, identifies three key trends: first, the east-west gap is pronounced, with central, western, and northeastern regions combined having only 105 firms; second, Guangdong's firms have the strongest technology profile, concentrated in EVs, electronics, and digital tech, but lack 'waist-level' support outside core cities; third, strategic emerging industries (new energy, AI, semiconductors) are becoming the new competitive focus, with provinces like Anhui and Sichuan leveraging strong capital-city strategies to foster advanced manufacturing clusters. Traditional resource-heavy provinces like Shandong, Hebei, and those in the northeast face transition pressure due to over-reliance on cyclical industries such as steel and coal.
Read sourceChina's Top 500 Private Firms: Zhejiang Leads, Strategic Industries Reshape Regional Competitiveness
An analysis by the 21st Century Business Herald, based on the All-China Federation of Industry and Commerce's '2026 China Top 500 Private Enterprises' list, reveals that the 500 firms generated total revenue of 44.9 trillion yuan, nearly 30% of China's 2025 GDP. The report highlights three key features of regional competition. First, eastern coastal regions dominate, accounting for 79% of listed firms and 85% of total revenue, with Zhejiang (104 firms), Jiangsu (90), and Guangdong (49) leading. Second, strategic emerging industries are becoming a new competitive focus, with provinces like Anhui (12 firms) concentrating on new energy, materials, and AI, while traditional resource-rich provinces like Shandong and Hebei face transition pressure. Third, the 'strong capital city' strategy in central and western regions is proving effective, with firms concentrated in cities like Hefei, Chengdu, and Wuhan. Guangdong's private firms are noted for the strongest tech profile, featuring Huawei, Tencent, and BYD, but lack 'waist-level' support outside the Pearl River Delta. The report concludes that the Yangtze River Delta and Pearl River Delta remain the dual cores of China's private economy.
Read sourceShow 3 older updatesHide older updates
China's Top 500 Private Firms Show Regional Shifts: Fujian and Anhui Rise, Hubei and Chongqing Decline
An analysis of the 2026 China Private Enterprise 500 list, released by the National Federation of Industry and Commerce on September 22, reveals significant regional shifts. Zhejiang, Jiangsu, Shandong, and Guangdong remain the top four provinces, accounting for over 60% of listed firms, though their individual counts have slightly changed since 2022. The most notable changes are in mid-tier provinces: Fujian and Anhui each gained five listed firms, the largest increase, driven by different growth models. Anhui's rise is attributed to a hard-tech chain breakthrough in new energy and AI, while Fujian's growth stems from a mix of manufacturing, consumer brands, and global trade. Conversely, Hubei lost seven firms and Chongqing lost five, primarily due to the exit of real estate-related companies. The article notes that the overall entry threshold for the 500 list fell to 256 billion yuan in 2026 from 263.7 billion yuan in 2022, while total revenue grew 17.2%, indicating growth is concentrated among top-tier firms. The analysis presents these changes as a reflection of a broader economic transformation from traditional sectors like real estate to new industries such as new energy and technology.
Read sourceChina's Top 500 Private Firms: Regional Shifts Show Rise of Fujian and Anhui, Decline of Hubei and Chongqing
An analysis of the 2026 China Private Enterprise 500 list, released by the National Federation of Industry and Commerce on September 22, reveals significant regional shifts over the past five years (2022-2026). Zhejiang, Jiangsu, Shandong, and Guangdong remain the top four provinces, accounting for over 60% of listed firms, though their numbers have slightly declined except for Shandong. The most notable changes are in mid-tier provinces: Fujian and Anhui each added 5 firms, the highest net gain, driven by contrasting growth models. Anhui's rise is fueled by a hard-tech chain in new energy (e.g., Sungrow, NIO, Gotion High-tech) and AI/semiconductors (iFLYTEK). Fujian's growth stems from a diversified model combining manufacturing (CATL, Fuyao Glass), consumer brands (Luckin Coffee), and global trade. Conversely, Hubei lost 7 firms and Chongqing lost 5, primarily due to the exit of real estate companies. Shaanxi also saw a decline, with its two former billion-dollar firms entering bankruptcy. The report attributes these shifts to a structural transformation of regional economies, moving away from real estate towards new energy, technology, and advanced manufacturing.
China's Top 500 Private Firms: Regional Shifts Reveal Winners and Losers in Economic Transition
An analysis of the 2026 China Private Enterprise Top 500 list, published by the All-China Federation of Industry and Commerce on September 22, reveals significant regional shifts in the country's private sector. Zhejiang, Jiangsu, Shandong, and Guangdong remain the top four provinces by number of listed firms, accounting for over 60% of the total. However, the most notable changes are in the middle tier. Fujian and Anhui each added five firms over the past five years, becoming the fastest-growing provinces. Fujian's growth is driven by a mix of manufacturing (e.g., CATL), consumer brands (e.g., Luckin Coffee), and trade, while Anhui's rise is fueled by a hard-tech chain in new energy (e.g., Sungrow, NIO, Gotion High-tech) and AI/semiconductors (e.g., iFlytek). In contrast, Hubei lost seven firms and Chongqing lost five, primarily due to the exit of real estate-related companies. Shaanxi saw a continued decline, with its once-billion-yuan firms entering bankruptcy. The analysis attributes these shifts to a structural transition from traditional industries like real estate to emerging sectors such as new energy, AI, and recycling.
Read source