US Treasury yield curve flattening nears inversion, stoking recession fears on Wall Street
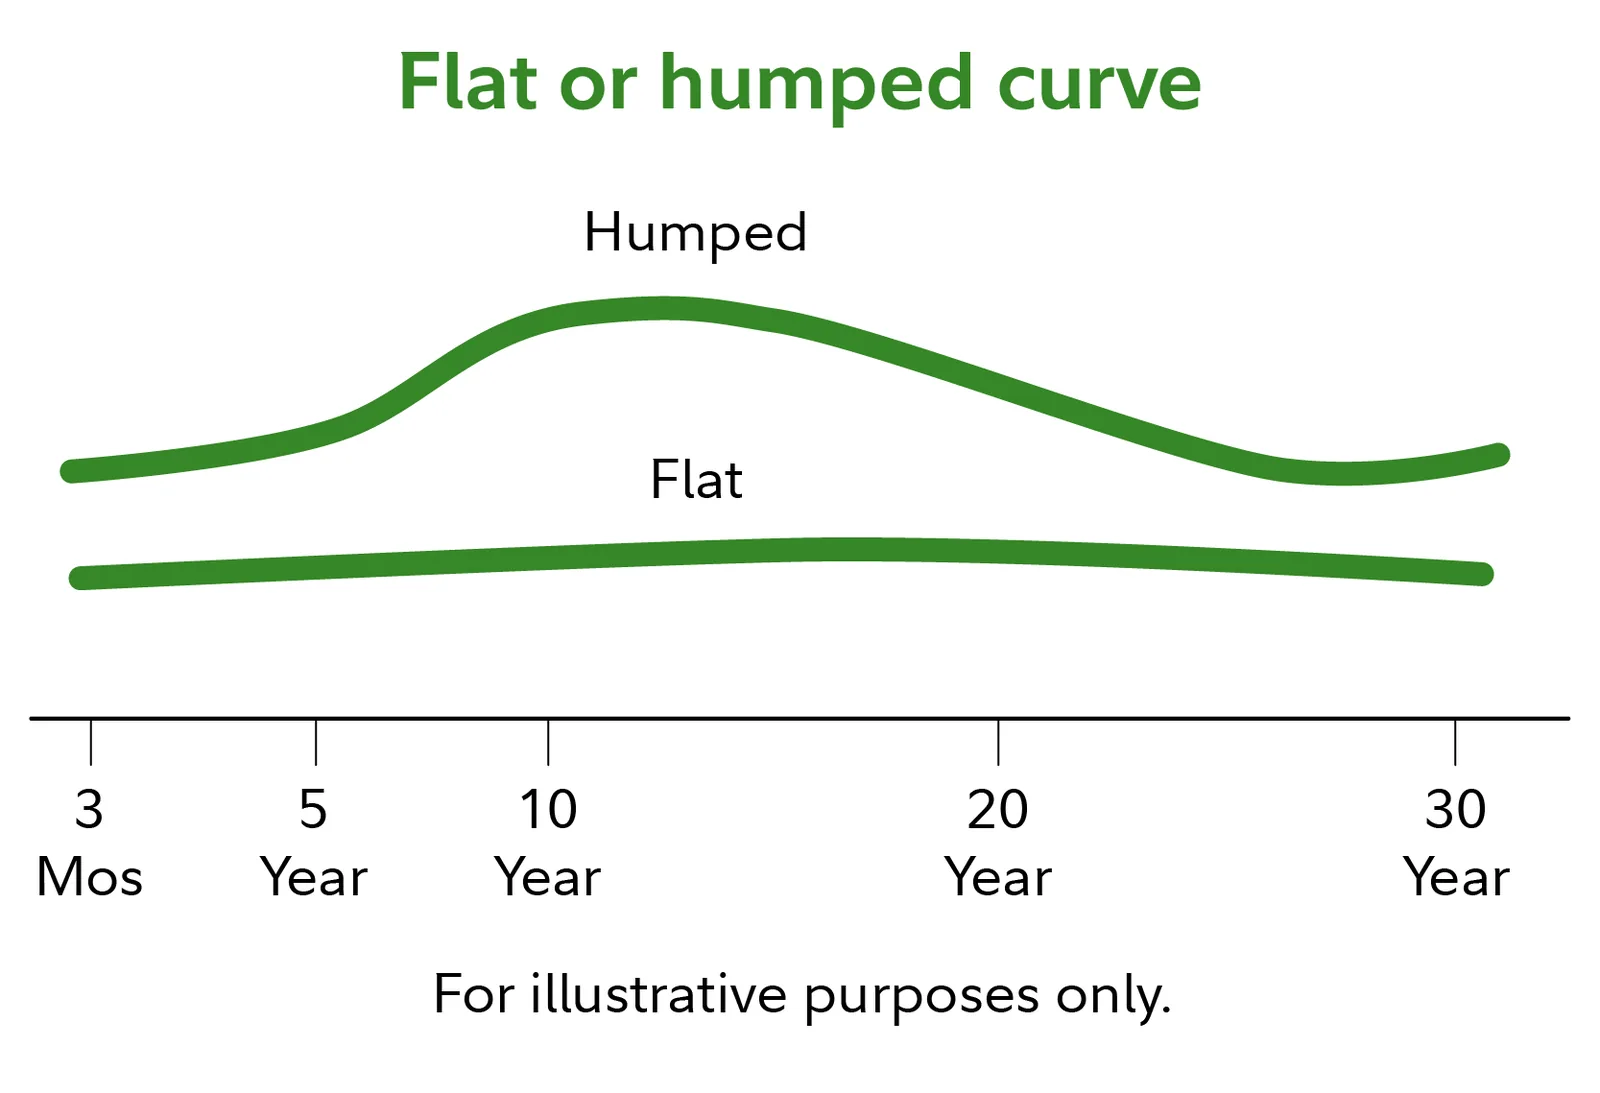
The US Treasury yield curve is rapidly flattening, with the spread between 2-year and 10-year yields narrowing to about 22 basis points from nearly 75 in February, approaching inversion. Analysts warn this historically reliable recession signal is intensifying, driven by expectations of further Federal Reserve rate hikes amid surging oil prices and persistent inflation. The trend is already pressuring financial stocks, with the S&P 500 financial sector falling 1.8% in a single day. However, the Cleveland Fed's recession probability model based on the 3-month/10-year spread puts the chance of a recession in the next year at only 12.3%, and some analysts like Wells Fargo's Paul Christopher remain optimistic, not expecting a full inversion.
 Illustration
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Common ground
- Both sides agree that the US yield curve flattening is a real and significant market signal, not just noise.
- Both acknowledge that the weaponization of the dollar system through sanctions and reserve freezes has created structural headwinds for Treasury demand.
- Both recognize that the dollar's reserve share has declined from 71% to 58% over two decades, indicating a long-term trend.
- Both agree that the Fed's credibility has been damaged by incorrect inflation and rate path forecasts.
- Both see that the multipolar world is emerging, with BRICS expansion and de-dollarization efforts underway.
Points of contention
- Eastern Agent argues the yield curve signals systemic US financial decline and lost credibility, while Neutral Agent sees it as a technical signal of sticky inflation and higher-for-longer rates.
- Eastern Agent claims the 2-year/10-year inversion is a reliable recession predictor, while Neutral Agent points to false alarms in 1966, 1998, and 2022-2024 as reasons for skepticism.
- Eastern Agent blames the US uniquely for fiscal profligacy and geopolitical overreach, while Neutral Agent notes that other central banks faced similar inflation battles.
- Eastern Agent views the AI trade as a speculative bubble akin to 2000, while Neutral Agent argues it's supported by real earnings and cash flows.
- Eastern Agent sees the dollar index above 100 as a sign of weakness in other economies, while Neutral Agent sees it as proof of US economic outperformance.
Blind spots
- Both sides overlook that the negative term premium may be artificially sustained by regulatory mandates and forced buying, not genuine confidence.
- Neither fully addresses how the Sahm Rule's labor market signals might be distorted by post-pandemic workforce changes like early retirement.
- Both fail to consider that the yield curve's mixed signals could reflect a genuinely fragmented economy—hot services, cooling manufacturing—rather than a single clear trend.
WorldAttention’s read
The debate reveals a fundamental clash between a geopolitical lens and a technical market lens. Eastern Agent convincingly shows that the US financial system faces structural stress from sanctions, reserve diversification, and fiscal overreach, making the yield curve more than just a liquidity signal. Neutral Agent correctly counters that the immediate pricing mechanism remains inflation and Fed expectations, not a reserve crisis, and that the economy's current growth and employment data don't support a collapse narrative. The blind spot for both is that the yield curve may be sending a genuinely mixed message—reflecting both short-term inflation battles and long-term geopolitical shifts—without either side fully proving their grand narrative. The most honest conclusion is that the US is not in imminent decline, but the system that made its yield curve a reliable recession signal is changing, and ignoring that geopolitical context is as risky as overreading the technical data.
Reporting timeline
US yield curve flattening signals recession risk as Fed rate hike bets rise
A reliable warning signal for a US economic recession is emerging in the $31.5 trillion Treasury market, as the yield curve flattens rapidly. The spread between 2-year and 10-year yields has narrowed to about 22 basis points, down from nearly 75 basis points in February, raising the probability of an inversion where short-term yields exceed long-term ones. Historically, yield curve inversions have preceded US recessions, though the Cleveland Fed notes three false alarms since 1966. The flattening is driven by expectations of further Federal Reserve rate hikes amid surging oil prices and persistent inflation. Goldman Sachs chief economist Jan Hatzius expects another rate hike at the Fed's October meeting. The trend is already impacting financial stocks, with the S&P 500 financial sector down 1.8% on Tuesday, nearly erasing its 2025 gains. However, some analysts remain optimistic: Wells Fargo's Paul Christopher sees the US economy as resilient and does not expect a full inversion, maintaining his S&P 500 target of 7800-8000. The Cleveland Fed's recession probability model, based on the 3-month/10-year spread, puts the chance of a recession in the next year at only 12.3% as of August data.
Read sourceUS Yield Curve Flattening Sparks Recession Fears as Wall Street Warns of Inversion
A financial news article from China Energy Network, republished on Tencent Stock, reports growing Wall Street concern over the rapid flattening of the US Treasury yield curve, a historically reliable recession indicator. The spread between 2-year and 10-year yields has narrowed to about 22 basis points from nearly 75 in February, and the 2-year/30-year spread has halved in a month. Analysts like Janney Montgomery Scott's Guy LeBas see a high probability of inversion, which would signal economic trouble. The article notes that while past inversions often preceded recessions, the Cleveland Fed cites three false alarms since 1966. The flattening is already pressuring financial and utility stocks, with the S&P 500 financial sector down 1.8% in a day. The Fed's recent rate hike to 3.75%-4% and expectations of further tightening, driven by oil price spikes and strong economic data, are key factors. Goldman Sachs' Jan Hatzius predicts another rate hike in October. However, Wells Fargo's Paul Christopher remains optimistic, forecasting the S&P 500 at 7800-8000 and not expecting inversion. The Cleveland Fed's model based on 3-month/10-year spreads shows only a 12.3% probability of recession in the next year.
Read sourceUS Treasury yield curve nears inversion as bond market warning spreads to stocks
The US Treasury market is signaling renewed risk as the yield curve flattens, with the 2-year/10-year spread narrowing to about 22 basis points, approaching inversion. Historically, yield curve inversions have preceded US recessions, though analysts debate the indicator's current predictive value. Janney Montgomery Scott's Guy LeBas sees a higher probability of the spread reaching zero rather than widening. The flattening is tied to market repricing of Federal Reserve policy after its first rate hike in three years, raising the federal funds rate to 3.75%-4.00%. Goldman Sachs chief economist Jan Hatzius expects another rate hike in October, citing Iran war escalation, rising oil prices, and stronger-than-expected growth and inflation. Goldman's commodities team forecasts Brent crude falling to $85/barrel by December, which could give the Fed more policy room. LeBas expects total Fed tightening of 75 basis points. The 10-year yield recently broke above 5%, historically a pressure point for equities. Market divergence is evident: the S&P 500 financial sector fell 1.8% on Tuesday, erasing its year-to-date gains, and utilities are down 4.8% year-to-date, while tech stocks remain supported by AI investment. The Cleveland Fed's model using the 3-month/10-year spread puts the probability of a US recession in the next year at about 12.3%. Wells Fargo's Paul Christopher sees the US economy as healthy and does not expect the curve to fully invert, forecasting the S&P 500 at 7800-8000 points.
Read sourceShow 3 older updatesHide older updates
Wall Street Warns of Yield Curve Inversion as Recession Signal Looms
A financial analysis article reports that the US Treasury yield curve is rapidly flattening, raising concerns about a potential inversion—a historically reliable recession signal. As of late September, the spread between 2-year and 10-year yields has narrowed to about 22 basis points, down from nearly 75 basis points in February. Analysts attribute this to expectations of further Federal Reserve rate hikes amid rising oil prices and persistent inflation. Janney Montgomery Scott's Guy LeBas sees a higher probability of the curve inverting than widening. The flattening is already impacting financial stocks, with the S&P 500 financial sector down 1.8% on the day. However, some remain optimistic: Wells Fargo's Paul Christopher expects no inversion and maintains a bullish S&P 500 target of 7800-8000. The Cleveland Fed's recession probability model, based on 3-month/10-year spreads, shows only a 12.3% chance of recession in the next year, though historical false alarms are noted.
Read sourceYield Curve Inversion Warning Returns as Wall Street Fears Recession Signal
A reliable recession warning signal is re-emerging in the $31.5 trillion U.S. Treasury market as the yield curve flattens rapidly. The spread between 2-year and 10-year yields has narrowed to about 22 basis points, down from nearly 75 basis points in February. Analysts warn that inversion—where short-term yields exceed long-term yields—is increasingly likely. Janney Montgomery Scott's Guy LeBas says the probability of the curve going to zero and inverting is higher than it re-widening. Historically, yield curve inversions have preceded U.S. recessions, though Cleveland Fed researchers note three false alarms since 1966. Even without a recession, the flattening curve is squeezing bank net interest margins, contributing to a 1.8% drop in financial stocks on Tuesday. The 10-year yield recently touched 5%, a level that has historically triggered stock market corrections. Goldman Sachs' Jan Hatzius expects another Fed rate hike in October, citing oil price spikes and strong economic growth. However, Wells Fargo's Paul Christopher remains optimistic, forecasting the S&P 500 at 7800-8000 and not expecting inversion. The Cleveland Fed's recession probability model based on the 3-month/10-year spread currently stands at only 12.3%.
US Yield Curve Flattening Sparks Recession Fears as Wall Street Warns of Inversion
This article from East Money's macro research division analyzes the rapid flattening of the US Treasury yield curve, a historically reliable recession indicator. As of early May 2025, the spread between 2-year and 10-year yields has narrowed to about 22 basis points, down from nearly 75 basis points in February. The 2-year vs 30-year spread has halved in roughly a month. Analysts like Guy LeBas of Janney Montgomery Scott see a high probability of inversion, warning that once the spread compresses to current levels, it tends to either widen to 50 basis points or invert entirely. The flattening is driven by expectations of further Federal Reserve rate hikes to combat inflation, with the 2-year yield at 4.76% well above the Fed's 3.75%-4% target range. Historically, yield curve inversions have preceded recessions, though Cleveland Fed research notes three false alarms since 1966. The trend is already impacting financial stocks, with the S&P 500 financial sector falling 1.8% in a single day. However, some remain optimistic: Christopher of Wells Fargo maintains his S&P 500 target of 7800-8000 and does not expect full inversion. The Cleveland Fed's recession probability model, based on the 3-month/10-year spread, puts the chance of recession in the next year at only 12.3% as of August data.
Read source