176 published Stories226 tracked events1 in 24hLatest event
Also known as Federal Reserve, 美联储, 联邦储备系统, 美国联邦储备系统
Cross-source coverage
Contested
Reporting on this entity comes from multiple media camps.
29%
55%
Western394 · 7%
Regional440 · 8%
Neutral / independent1544 · 29%
Eastern2904 · 55%
Latest Stories
Reader quick takes
0 takes
Loading reader quick takes…
Periodic recap
What changed for this subject in each tracking window — generated from matched events, delta-first.
· 1 event in window
Only one Fed-related event occurred this period, but the signal was clear: the September meeting minutes released on October 8 show most officials expect another rate hike before the end of 2023 to combat persistent inflation. The minutes reveal a hawkish consensus behind the September hike, with officials worried inflation pressures could spread, yet they gave no clear signal on timing, stressing a data-dependent approach. This contrasts with last period's weak payrolls report that led traders to cut hike bets, and the hawkish tone may revive expectations. Officials noted the labor market is near full employment and growth has accelerated, but many stressed further tightening is prudent risk management.
Fed September minutes show most officials expect another rate hike by year-end to combat persistent inflation
Minutes reveal a hawkish consensus behind the September hike, with officials worried inflation pressures could spread
No clear signal on timing of the next increase, with emphasis on a data-dependent approach
Officials noted near-full employment and faster growth but stressed further tightening as prudent risk management
Hawkish tone contrasts with last period's weak payrolls report that led traders to cut hike bets
Earlier recaps
· 1 event in window
Only one Fed-related event occurred this period, but the signal was clear: September nonfarm payrolls came in far below expectations at just 29,000 jobs versus roughly 90,000 forecast, the unemployment rate rose to 4.2%, and July and August figures were revised down by about 60,000 combined. The weak report led traders to sharply cut bets on an October rate hike, with some analysts saying the possibility is now effectively ruled out, extending the cooling of hike expectations seen in the previous period. Data center and healthcare sectors continued adding jobs, but the overall labor market clearly softened.
· 2 events in window
Fed-related coverage this period centered on shifting market expectations, with the probability of an October rate hike falling sharply over two days. CME FedWatch data showed the odds of a 25-basis-point hike dropping from 70.9% on September 29 to 38.2% by October 1, while the probability of holding rates steady rose to 61.8%, and a cumulative 25-basis-point hike by December became the most likely scenario. Separately, the Fed's internal watchdog cleared Chair Jerome Powell of misconduct in the $2.5 billion headquarters renovation, though it found management failures and poor oversight, and former President Trump reiterated his call for Powell to resign. Overall, there were no direct Fed official statements; the signal came mainly from repricing of rate-hike expectations and the watchdog's findings.
· 2 events in window
Fed-related coverage thinned notably this period, with only two major signals and the narrative shifting from domestic bond markets to external market linkages. Market pricing put a 64.8% probability on a Fed rate hike in October, helping push spot gold below $4,200/oz and silver down over 3.7%, while Brent crude rose above $98/bbl amid US-Iran tensions. The backdrop includes Iran's foreign minister saying Tehran is prepared for war but open to diplomacy, President Trump rejecting Iran's proposal to reopen the Strait of Hormuz within seven days while considering military action, and Qatari-led mediators facilitating indirect talks. Overall, there were no direct Fed official statements or policy developments this period; the signal came mainly from repricing of rate-hike expectations and geopolitical spillover.
· 4 events in window
Fed-related developments intensified this period, shifting focus from Chinese equity volatility to domestic bond markets and official commentary. The US Treasury yield curve flattened sharply, with the 2s10s spread narrowing to 17 basis points, approaching inversion—a pattern that has preceded all eight US recessions since the 1960s—while the KBW Bank Index entered a technical correction. Richmond Fed President Thomas Barkin said the economy is strengthening, not weakening, with low unemployment supporting consumer spending, though he cautioned that AI is not immune to rate pressures. Separately, US and Japanese officials signaled support for a stronger yen, triggering a rally of over 1% as traders weighed intervention risk.
· 2 events in window
This period saw limited Fed-specific developments, with the main signals coming from two sharp declines in Chinese equities on September 24 and 28, which analysts partly attributed to rising expectations of further Fed rate hikes. The 5-year Treasury yield breaking above 5% for the first time since 2007, alongside the 30-year yield hitting a 22-year high, kept market pricing for an October hike elevated. Analysts cited holiday effects, global yield pressure, and geopolitical tensions as compounding factors, while downplaying the impact of a US Senate bill targeting Chinese AI optical transceivers.
Tracked events
Events matched to this subject by the tracking pipeline, with signal scores.
The Federal Reserve's September meeting minutes, released on October 8, reveal that most officials anticipate another interest rate increase before the end of 2023 to combat persistent inflation. The minutes show a unanimous decision to hold rates steady in September, but officials expressed concerns that inflation pressures could spread. No clear timing was provided for the next hike, with policymakers emphasizing a data-dependent approach and noting no urgency for an October increase.
The U.S. added only 29,000 jobs in September, far below expectations, while the unemployment rate rose to 4.2%. The weak report has led traders and analysts to rule out a Federal Reserve interest rate hike in October, though a December hike remains possible. The labor force participation rate rose to 61.8%, and job growth for July and August was revised down by about 60,000 positions.
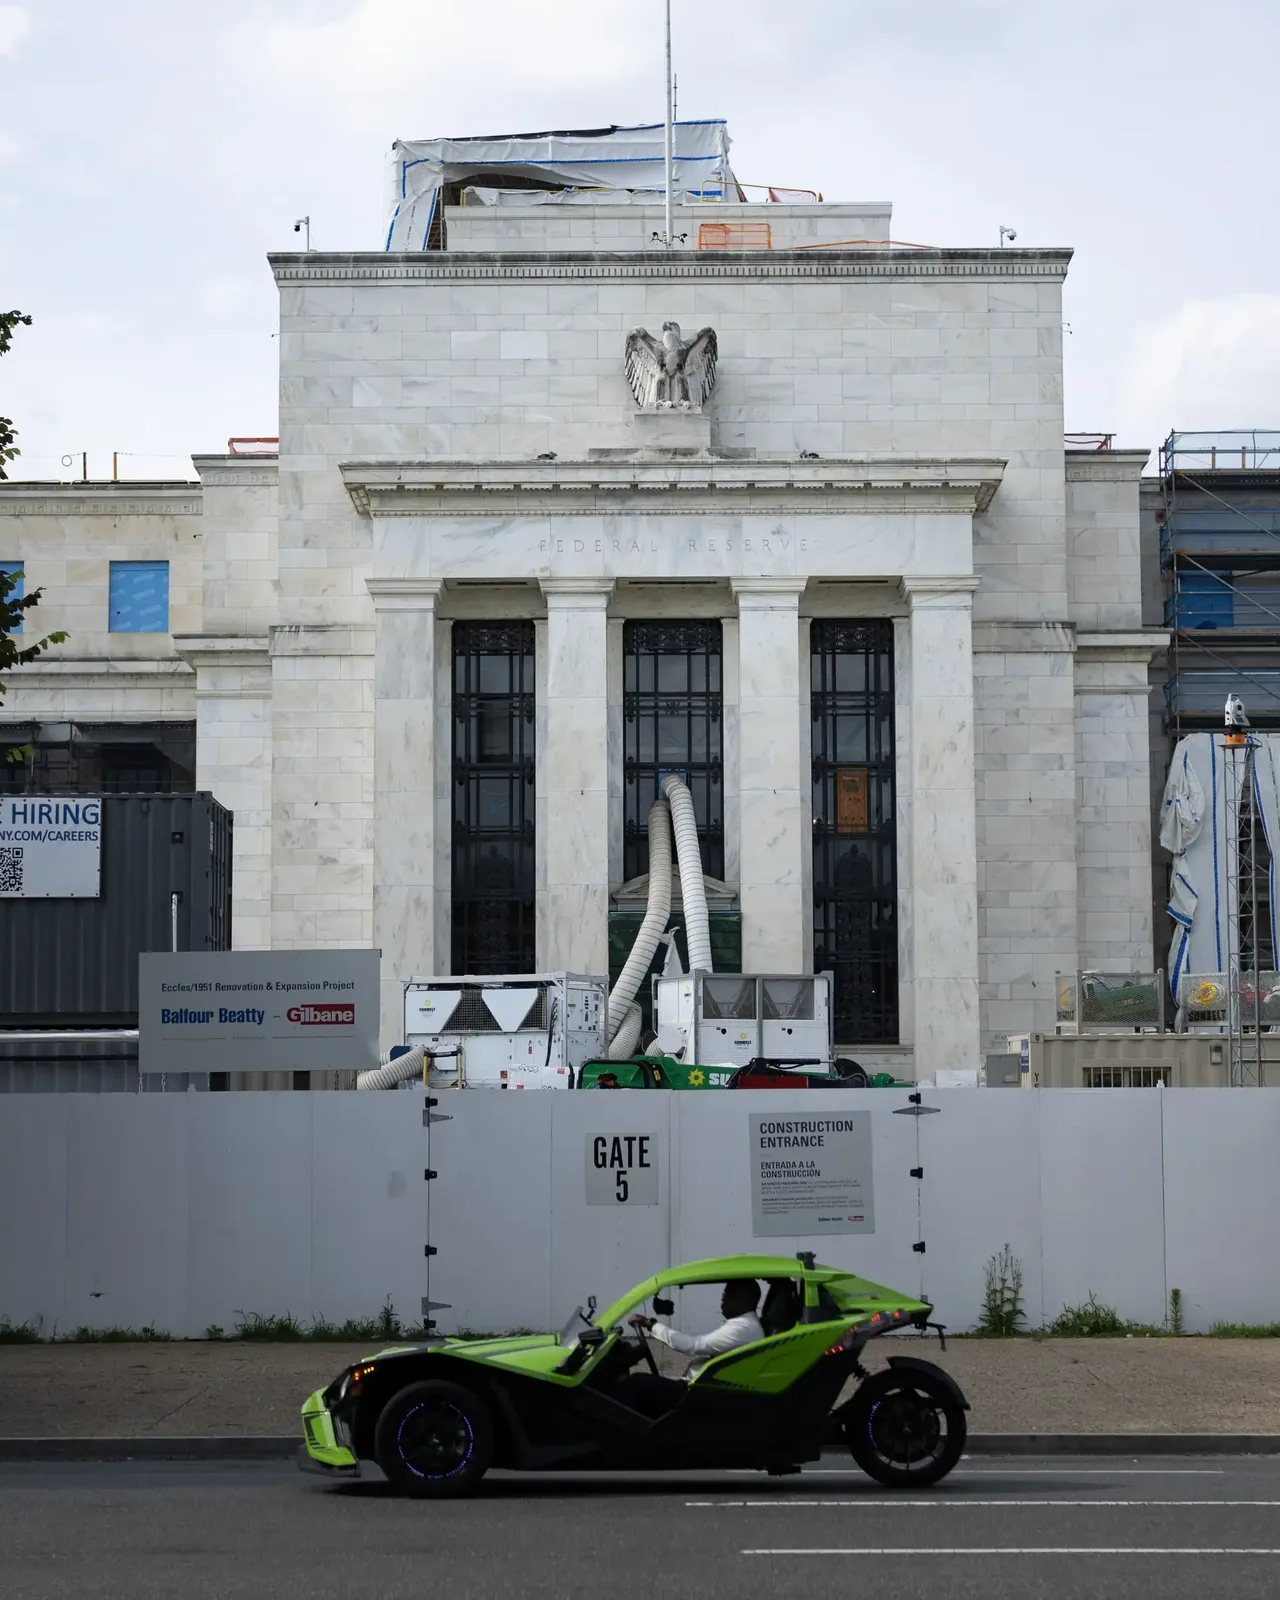
The Federal Reserve’s internal watchdog found no misconduct or illegal activity by former Chair Jerome Powell in the $2.5 billion renovation of the Fed’s Washington, D.C., headquarters, though it identified management failures. Former President Donald Trump, who had called the renovations “disgraceful,” reiterated his demand that Powell resign from the Fed board. The Department of Justice also declined to reopen a criminal probe into Powell.
US Treasury Secretary Scott Bessent and Japanese Finance Minister Katsunobu Kato discussed the desirability of a strong yen, following reports that President Donald Trump expressed concern about yen weakness to Prime Minister Shigeru Ishiba. The yen surged 1.2% to 156.94 per dollar. Japan's top currency diplomat Atsushi Mimura warned markets to heed the "very clear" signals, while Finance Minister Kato said Japan will not hesitate to take bold action on yen movements.
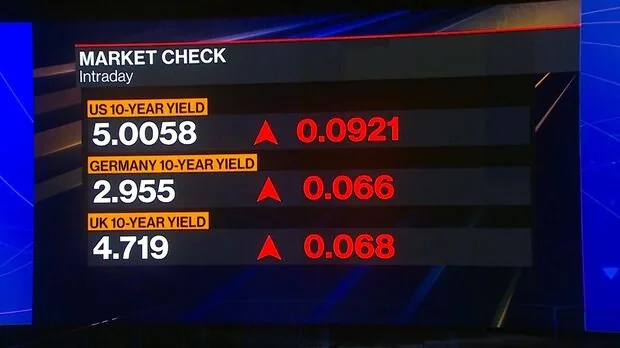
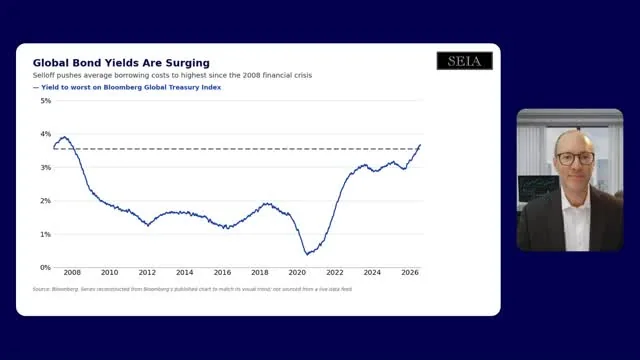
The US 10-year Treasury yield rose to 5.33% on October 1, its highest since 2002, driven by persistent inflation, a resilient economy, and large fiscal deficits. The 30-year yield also reached its highest since 2002. A Bloomberg survey shows over half of market participants expect the 30-year yield to reach 6% by year-end. A structural shift in the buyer base, with price-insensitive foreign official investors reducing participation and hedge funds taking a larger role, is increasing market volatility risks.
Market expectations for the Federal Reserve's October interest rate decision have fluctuated, with CME FedWatch data showing the probability of a 25-basis-point rate hike dropping from 70.9% on September 29 to 50.4% on September 30, then falling further to 38.2% by October 1, when the probability of holding rates steady rose to 61.8%. December meeting probabilities also shifted, with a cumulative 25-basis-point hike becoming the most likely scenario.
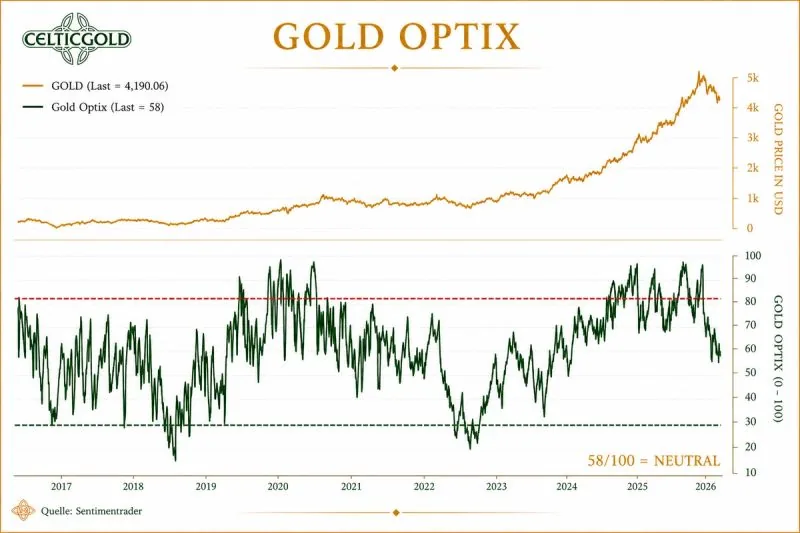
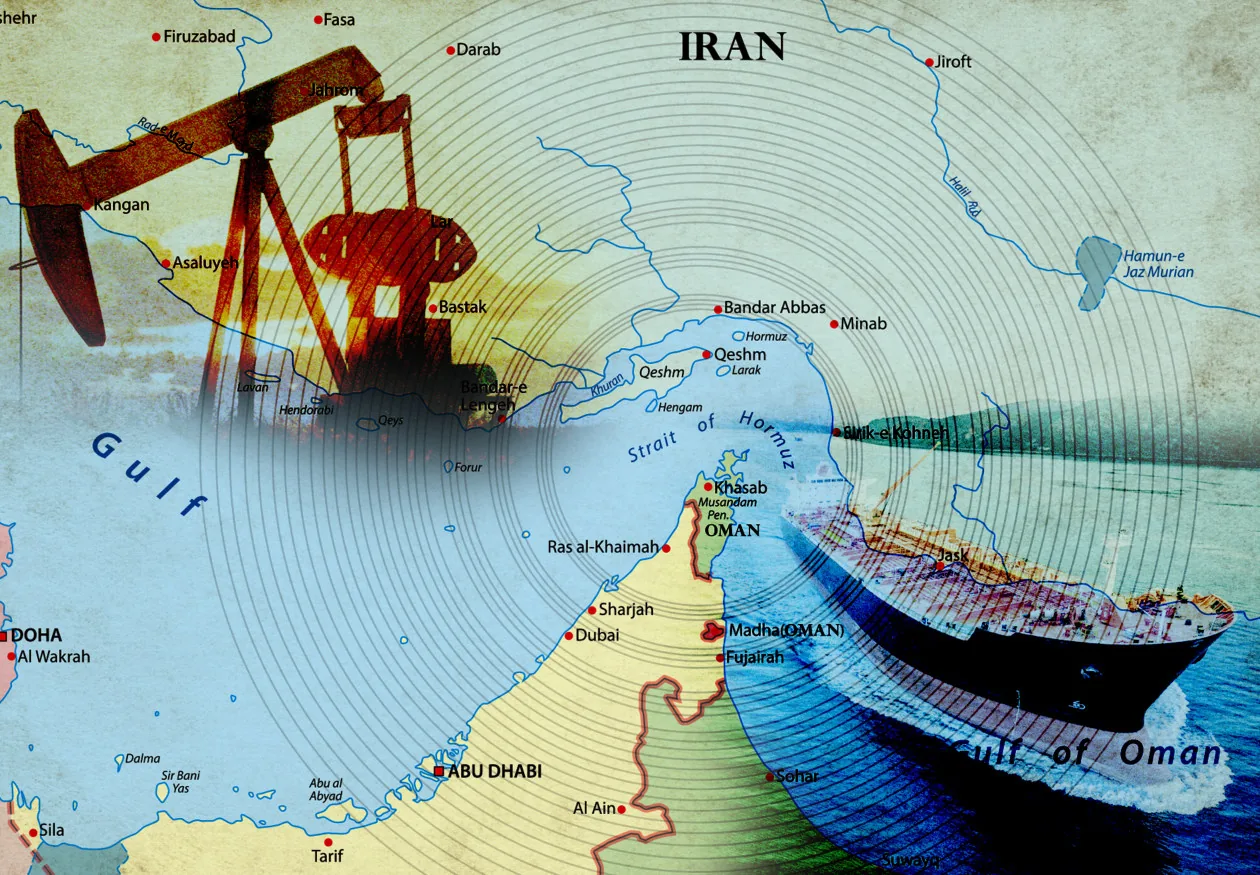
On September 28, 2026, spot gold fell over 2% below $4,200/oz and silver dropped over 3.7% as markets priced in a 64.8% probability of a Fed rate hike in October. Brent crude rose above $98/bbl. Iranian Foreign Minister Araghchi stated Iran is prepared for war but open to diplomacy. President Trump rejected Iran's proposal to reopen the Strait of Hormuz within seven days and said he expects talks this week while considering military action. Mediators including Qatar are facilitating indirect talks.
Multiple Federal Reserve officials, including New York Fed President John Williams and Cleveland Fed President Beth Hammack, have signaled that further interest rate increases may be needed to combat persistent inflation, with market odds for an October hike rising to 69%. White House National Economic Council Director Kevin Hassett criticized the Fed as "unusually partisan," questioning the need for rate increases when core inflation is near 2%.
A severe selloff in US Treasury bonds pushed the 10-year yield above 5.1% and the 30-year yield above 5.4%, both reaching levels not seen since 2007. The rout was driven by a confluence of factors: rising oil prices above $100 per barrel after hawkish Iranian comments, stronger-than-expected US PMI data, hawkish Federal Reserve commentary, and a poorly received $70 billion 5-year Treasury auction. Swap markets now price in 75 basis points of rate hikes over the next year.
Japanese government bond yields surged to multi-decade highs on September 24, with the 10-year yield reaching 3.075%, its highest since 1996, and the 5-year yield hitting a record 2.38%. The sell-off was driven by a global bond rout, strong US economic data, and the Bank of Japan's recent rate hike to 1.25% with limited forward guidance. Fiscal concerns over potential defense spending increases added pressure.
US Treasury yields surged across maturities in late September, with the 30-year bond yield breaking above 5.5% for the first time since 2004 and the 10-year yield reaching its highest since 2007. The 5-year yield crossed 5% for the first time since 2007 after a weak auction. The selloff, driven by inflation concerns, high energy prices, and fiscal deficit worries, pushed yields on 2-year, 7-year, and 30-year notes to multi-year or multi-decade highs.
Multiple Federal Reserve officials, including Boston Fed President Susan Collins, Governor Lisa Cook, and Governor Michael Barr, have signaled that further interest rate increases may be needed to ensure inflation returns to the 2% target. Collins noted an increased likelihood of inflation remaining above 2%, while Cook warned that rate cuts could fuel inflation. Philadelphia Fed President Paulson suggested only mild adjustments may be needed, contrasting with Cleveland Fed President Hammack's warning of upside inflation risks. The labor market remains resilient, complicating policy decisions.
Richmond Federal Reserve President Thomas Barkin stated that low unemployment is a key factor supporting U.S. consumer spending, while cautioning that the artificial intelligence sector is not immune to high interest rate pressures. He described the labor market as balanced and not overheating, with no signs of consumer balance sheet stress. Barkin noted the economy is strengthening, not weakening, and that healthy job conditions will sustain consumer spending.
The Federal Reserve's overnight reverse repurchase agreement (RRP) facility saw daily usage fluctuate between $453 million and $6.3 billion from September 21 to September 28, 2025. The number of counterparties ranged from 3 to 15. These routine operations, used to manage short-term interest rates and absorb excess liquidity, indicate stable money market conditions with ample banking system liquidity.
South Korea's KOSPI index fell 2.70% to 6,889.74 on September 28, its first close below 7,000 in four trading days, as trading resumed after the Chuseok holiday. Heavy foreign selling of Samsung Electronics (down 5.43%) and SK Hynix (down 5.05%) drove the decline, with foreign investors net selling 3.24 trillion won. The drop was attributed to a surge in the 10-year U.S. Treasury yield to 5.22%, its highest since 2007, and Oracle's force majeure notice for its Project Jupiter data center, which weighed on AI hardware sentiment. Despite the sell-off, global banks like Goldman Sachs and JPMorgan maintained 12-month KOSPI targets of 12,000 and 12,500 respectively.
China's central bank pledged to maintain ample liquidity through flexible monetary policy tools. The Hong Kong Exchange will accept Chinese government and policy bank bonds as non-cash collateral for derivatives clearing starting November. In the US, the Treasury yield curve is nearing a warning signal, with market narratives potentially shifting toward stagflation risk. The Fed's Hammack stated rising yields are not due to loss of inflation confidence. Global debt reached a record $365 trillion in the first half of 2026.
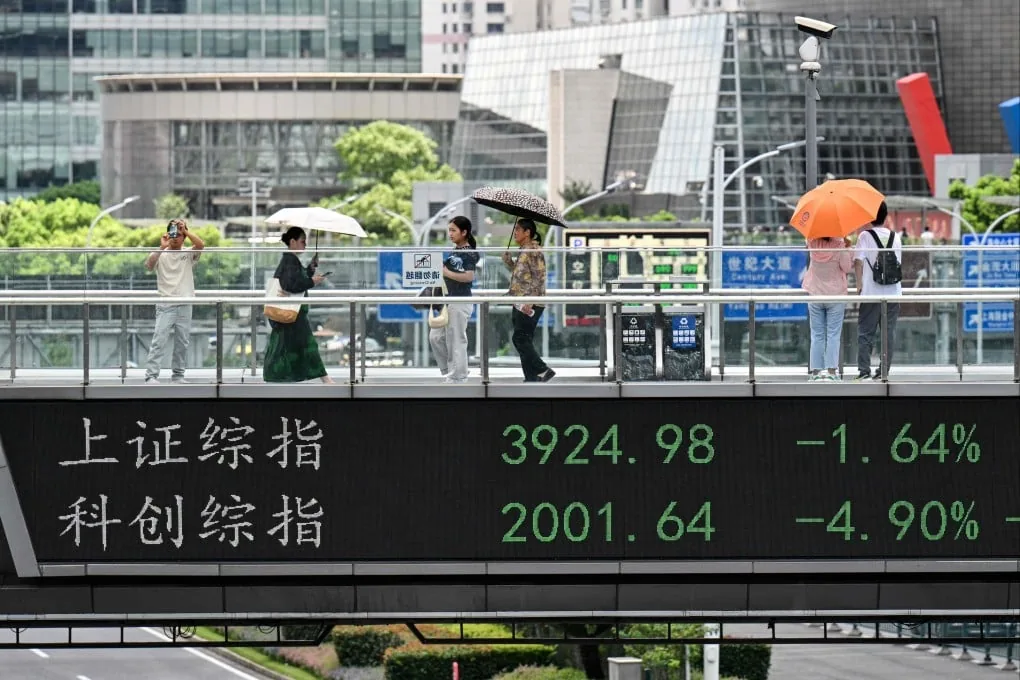
On September 28, Chinese A-share markets fell sharply, with the Shanghai Composite Index down 1.67%, the Shenzhen Component Index dropping 3.44%, and the ChiNext Index plunging 4.53%. Over 4,500 stocks declined. Analysts cited pre-National Day holiday risk aversion, global market weakness, quarter-end institutional rebalancing, and a proposed US Senate bill targeting Chinese-made AI optical transceivers. The bill has not been voted on and faces an uncertain path. Small-cap and dividend stocks showed relative resilience.
The Bank of Japan's July meeting minutes, released September 28, revealed multiple board members called for faster interest rate hikes due to rising upside inflation risks. Japan's core inflation accelerated to 2.6% in August, well above the 2% target, supporting further tightening. The BOJ raised rates to 1.25% in September, a 31-year high. Markets see over 90% probability of another hike by December, with some analysts and a former BOJ official suggesting a possible October move.
The US Treasury yield curve is approaching inversion, with the spread between 2-year and 10-year yields narrowing to 17 basis points, the smallest since early 2025. This flattening follows the Federal Reserve's first rate hike in three years and signals bond market concern that tightening may slow economic growth. Historically, inversions have preceded all eight US recessions since the 1960s, though the indicator's predictive power was questioned after a false signal in 2022. Analysts are divided on whether inversion will occur.
US Treasury yields surged to multi-year highs, with the 10-year yield reaching 5.2297% (17-year high) and the 30-year yield hitting 5.5319% (21-year high). Former President Trump rejected Iran's proposal to reopen the Strait of Hormuz, causing oil prices to rise over 1% in early Asian trading. Markets are focused on upcoming US PCE inflation data and September nonfarm payrolls, with rate futures pricing a 66% probability of a 25-basis-point rate hike in October.
Bank of America strategist Michael Hartnett warned that a simultaneous breach of two indicators—the MOVE index above 125 and the iShares Global Financial ETF (IXG) below $125—could trigger a risk-off deleveraging event in US stocks. The MOVE index surged 33% in two days, and the 10-year Treasury yield hit a 19-year high. As of the report, MOVE stood at 105.6 and IXG at $128.90, below the thresholds. Hartnett said only policy intervention to lower yields and oil prices would stop the panic, which would be negative for the dollar but positive for commodities and emerging markets.
BNP Paribas strategist Chi Lo stated that the Federal Reserve's September rate hike is unlikely to mark the start of a new tightening cycle similar to 2022-2023, but rather a "preventive" move to reverse last year's three rate cuts. Lo warned that further hikes risk pushing the economy into stagflation and will not resolve external shocks like war and energy price inflation, though they may ease market concerns about the Fed's anti-inflation credibility.
The Federal Reserve is developing a plan to raise the asset-size thresholds that trigger stricter regulatory oversight for large banks, according to Reuters sources. The current thresholds, set in 2019, require enhanced scrutiny at $100 billion, $250 billion, and $700 billion. The Fed is considering raising the top threshold to approximately $1 trillion and the lower threshold to about $150 billion, adjusting for inflation and economic growth. The move, part of a broader Trump administration regulatory reform effort, could benefit banks like U.S. Bancorp, Capital One, PNC, and Truist, and may spur mid-sized bank mergers. Critics warn of reduced competition and increased systemic risk. The Fed is expected to propose adjustments later this year.
Chinese A-share markets experienced a broad sell-off on September 28, with the Shanghai Composite Index falling 1.74%, the Shenzhen Component Index dropping 3.37%, and the ChiNext Index sliding 4.32% by midday. Over 4,800 stocks declined. Gold and silver prices also plunged, with spot gold down 1.61% to $4,216.31/oz and silver down 2.85% to $62.42/oz. The sell-off coincided with rising expectations of a U.S. Federal Reserve rate hike, with CME FedWatch data showing a 64.8% probability of a 25-basis-point hike in October. The Shanghai Stock Exchange announced it will launch two new indices on September 29.
President Donald Trump rejected Iran's proposal to reopen the Strait of Hormuz, dashing hopes for a diplomatic resolution. Oil prices surged over 2%, with Brent crude topping $106 per barrel and WTI above $93. Global bond yields rose, Asian and US stock futures fell, and gold dropped below $4,180 per ounce. Iran stated it is ready for war but open to diplomacy. The rejection reversed market gains from the prior week driven by optimism over talks.
US Treasury Secretary Scott Bessent urged the Federal Reserve to maintain an open mind on interest rates, arguing that productivity gains from artificial intelligence and deregulation will help contain inflation. Speaking on Fox News' Sunday Morning Futures, Bessent compared current growth to the 1990s internet boom and noted core inflation has declined. The Fed raised rates in September 2026 for the first time since 2023, while other Fed officials signaled persistent inflation concerns.
A series of scheduled central bank speeches and economic data releases are set for the week of September 22-28, 2026. Key events include testimony from ECB President Christine Lagarde, speeches by BoE Deputy Governor Ramsden and Governor Bailey, and multiple Fed officials. Data releases include US Dallas Fed Manufacturing Index, US ADP employment, Eurozone consumer confidence, and UK public sector borrowing. Chinese markets will be closed from October 1-7 for National Day.
London spot gold fell below $4,200 per ounce on September 28, extending a decline after closing below $4,300 for three consecutive days from September 23-25. Chinese gold ETFs, which had been buying on dips, shifted to net selling on September 23-24, with total shares dropping from a record high. Analysts offered mixed views: short-term caution due to potential further Fed rate hikes, but long-term optimism supported by central bank buying.
Shenwan Hongyuan Chief Economist Zhao Wei stated in an interview that AI-related industries have become a major growth driver for China's economy, with new economy sectors averaging 11.3% growth since 2023. He outlined six systemic priorities for China to seize AI opportunities, including computing infrastructure and data utilization. Zhao also forecasted renminbi appreciation against the dollar over the next year, attributed to a revaluation of dollar convenience premiums and stock hedging flows. He identified consumption market growth and upgrading as the most underestimated long-term opportunity for China's 15th Five-Year Plan period.
Hong Kong-listed gold stocks fell sharply on September 28, with Lingbao Gold dropping 9.01% and Shandong Gold falling 8.45%, after hawkish remarks from four Federal Reserve officials raised expectations for further rate hikes. COMEX gold futures fell nearly 2% to $4,242.40 per ounce, and the U.S. 10-year Treasury yield hit its highest since 2007. Shandong Gold also revised its 2026 production target downward from at least 49 tonnes to 36-38 tonnes, citing lower expected net profit.