Tianzhun Technology H1 2026 Revenue Surges 48.6% on AI Equipment and CPO Inspection Orders
Tianzhun Technology reported H1 2026 revenue of RMB 887 million, up 48.6% year-on-year, and net profit of RMB 98 million, a 793.92% increase. The company secured its first small-batch order from Foxconn Industrial Internet for CPO online AOI inspection equipment, marking entry into optical communications. Its semiconductor associate Suzhou Xixing Semiconductor delivered a TB2000 bright-field inspection tool (14-28nm) to a leading foundry for trial. New orders reached RMB 2.104 billion, up 62.2%. Analysts at Huaxin Securities and Xiangcai Securities issued 'Buy' ratings.
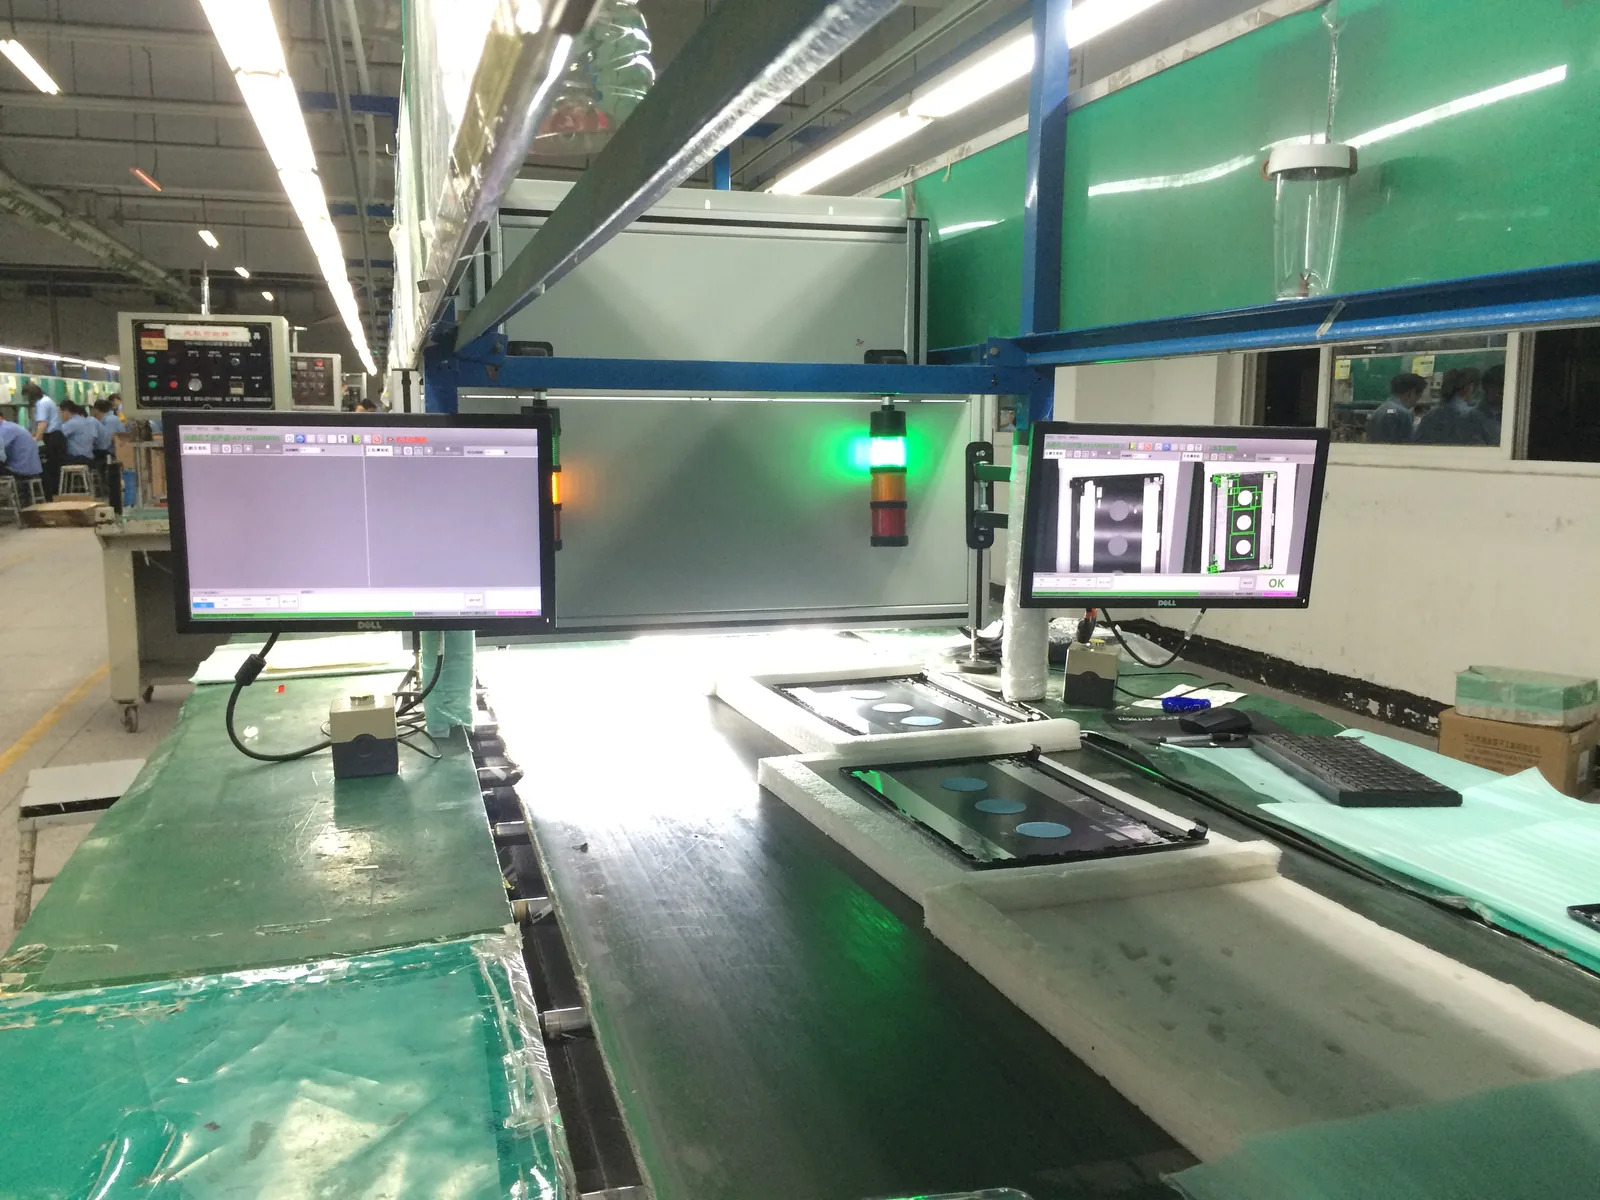 Illustration
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Common ground
- Tianzhun Technology's 48% revenue growth and 14-28nm inspection tools show real engineering progress in China's semiconductor industry.
- Western export controls have not stopped China's tech development and may have accelerated domestic innovation.
- KLA and Applied Materials had a long-standing duopoly in high-end inspection equipment, which Tianzhun is now challenging.
- The Global South is caught in the middle of a tech cold war between China and the West.
Points of contention
- Whether Tianzhun's success is a reactive response to Western sanctions or part of a long-term Chinese strategy.
- Whether Chinese tech exports create new dependencies for the Global South or break existing monopolies.
- Whether Tianzhun's technology is purely civilian or has significant surveillance and military applications.
- Whether China's labor and environmental practices are improving or still exploitative.
Blind spots
- The debate largely ignored the environmental costs of semiconductor manufacturing and their impact on local communities.
- There was little discussion of how ordinary workers in Chinese factories experience automation and wage conditions.
- The ethical implications of dual-use technology for surveillance and social control were only briefly touched on.
- The perspective of Global South countries themselves—what they actually want from tech suppliers—was missing.
WorldAttention’s read
This roundtable showed that Tianzhun Technology's rapid growth is a real achievement in China's push for semiconductor self-sufficiency, but opinions split sharply on what it means. The Eastern Agent sees it as a win for fair competition and multipolarity, breaking Western monopolies and giving developing nations more choices. The Regional Agent argues this success comes with hidden costs—new dependencies for the Global South, labor and environmental issues, and the risk of enabling surveillance states. Both sides agree that Western export controls backfired by speeding up Chinese innovation, but they disagree on whether that's good for the world. The biggest blind spot was the lack of voices from workers, local communities, and Global South countries themselves, who are the ones actually living with the consequences of this tech race. Ultimately, Tianzhun's story is not just about revenue and tools—it's about who benefits from technological power and who pays the price.
Reporting timeline
Tianzhun Industrial AI Equipment Enters New Cycle Driven by Dual Core and Multi-Line Resonance
A research report from Xiangcai Securities analyzes Tianzhun Technology (688003), an industrial AI equipment platform driven by an 'AI × Precision Optomechatronics' dual-core strategy. The company has formed three business matrices: AI measurement & inspection equipment, AI process equipment, and embodied brain solutions. In the first half of 2026, Tianzhun reported revenue of 887 million yuan, a 48.6% year-on-year increase, and turned profitable on a non-GAAP basis. New orders reached 2.104 billion yuan, up 62.2%. Key growth drivers include optical communication inspection equipment for CPO/NPO scenarios, semiconductor front-end inspection equipment (TB1500, TB2000), and PCB equipment for AI servers. The embodied brain business, including humanoid robot controllers, saw revenue grow 141.6%. The report forecasts 2026-2028 revenue of 2.343 billion, 2.958 billion, and 3.545 billion yuan respectively, with net profits of 183 million, 257 million, and 327 million yuan. The analyst maintains a 'buy' rating, citing benefits from AI capex, optical communication upgrades, robot deployment, and semiconductor localization. Risks include weaker demand, margin pressure, and competition.
Read sourceTianzhun Technology's Dual-Core AI Platform Enters New Cycle with Three Business Matrices
Tianzhun Technology, an industrial AI equipment platform driven by an 'AI × Precision Optomechatronics' dual-core strategy, has formed three business matrices: AI measurement and inspection equipment, AI process equipment, and embodied brain solutions. In the first half of 2026, the company reported revenue of 887 million yuan, a 48.6% year-on-year increase, and turned profitable with a non-GAAP net profit of 10 million yuan. New orders reached 2.104 billion yuan, up 62.2%. The report highlights key growth drivers: AI measurement equipment is expanding into optical communication (CPO/NPO) and semiconductor front-end inspection; AI process equipment, particularly PCB LDI and laser drilling, benefits from AI server demand; and the embodied brain solutions segment, including humanoid robot controllers, saw revenue grow 141.6%. The brokerage, Xiangcai Securities, forecasts 2026-2028 revenue of 2.343 billion, 2.958 billion, and 3.545 billion yuan respectively, with net profits of 183 million, 257 million, and 327 million yuan. It maintains a 'Buy' rating, citing benefits from AI capex, optical communication upgrades, and semiconductor localization.
Read sourceTianzhun Technology Deepens AI Industry Chain Strategy, Expands Downstream Application Sectors
Tianzhun Technology (天准科技) released its 2026 semi-annual report, reporting revenue of 887 million yuan, up 48.63% year-on-year, and net profit attributable to shareholders of 98 million yuan, up 793.92%. The company is deepening its AI industry chain strategic layout, with AI measurement and inspection equipment revenue reaching 375 million yuan (+28.85%), AI process equipment revenue at 355 million yuan (+47.31%), and embodied brain solutions revenue at 158 million yuan (+141.60%). New orders in H1 2026 totaled 2.104 billion yuan (+62.20%), with orders on hand at 2.375 billion yuan (+49.61%). The company secured an initial small-batch order from Foxconn Industrial Internet for CPO online AOI inspection equipment, opening a new growth market in optical communications. In semiconductors, its associate Suzhou Xixing Semiconductor made progress with its TB2000 bright-field inspection tool (14-28nm) delivered to a leading foundry for trial, and a TB1500 tool (40nm) sold for mass production. Huaxin Securities forecasts 2026-2028 revenue of 2.533, 3.346, and 4.202 billion yuan respectively, with EPS of 0.88, 1.37, and 1.81 yuan, initiating coverage with a 'Buy' rating.
Read sourceShow 2 older updatesHide older updates
Huaxin Securities Initiates Buy Rating on Tianzhun Technology, Citing AI Strategy and Order Growth
Huaxin Securities analysts Zhuang Yu, You Shaowei, and Zhang Lu initiated coverage on Tianzhun Technology (688003) with a 'Buy' rating, following the company's 2026 semi-annual report. For the first half of 2026, Tianzhun reported revenue of 887 million yuan, up 48.63% year-on-year, and net profit attributable to shareholders of 98 million yuan, a surge of 793.92%. The analysts highlight the company's deepening AI industry chain strategy, with AI measurement and inspection equipment revenue reaching 375 million yuan (+28.85%), AI process equipment revenue of 355 million yuan (+47.31%), and embodied brain solutions revenue of 158 million yuan (+141.60%). New orders in H1 2026 totaled 2.104 billion yuan, up 62.20%, with orders on hand of 2.375 billion yuan. Key growth drivers include winning a CPO online AOI inspection equipment order from Foxconn Industrial Internet, opening a new market in optical communications, and progress in semiconductor inspection equipment through its investee Suzhou Xixing Semiconductor. The analysts forecast 2026-2028 revenue of 2.533, 3.346, and 4.202 billion yuan respectively, with EPS of 0.88, 1.37, and 1.81 yuan. Risks include macroeconomic conditions, R&D delays, competition, and demand shortfalls.
Read sourceTianzhun Technology Deepens AI Strategy, Wins CPO Inspection Order, Semiconductor Progress
Tianzhun Technology (688003) reported H1 2026 revenue of RMB 887 million, up 48.63% YoY, and net profit of RMB 98 million, up 793.92% YoY, driven by strong growth in AI inspection and manufacturing equipment. The company secured a first batch of online AOI inspection equipment orders from Foxconn Industrial Internet for CPO (Co-Packaged Optics) mass production, opening a new growth avenue in optical communications. In semiconductors, its associate Suzhou Xishi Semiconductor made progress with its TB2000 bright-field inspection tool for 14-28nm nodes delivered to a leading wafer foundry, and a TB1500 tool for 40nm nodes sold for mass production use. New orders in H1 2026 reached RMB 2.104 billion, up 62.20% YoY, with a backlog of RMB 2.375 billion. The report forecasts 2026-2028 revenue of RMB 2.533, 3.346, and 4.202 billion, respectively, with EPS of RMB 0.88, 1.37, and 1.81. Risks include macroeconomic headwinds, R&D delays, competition, and demand weakness. The analyst initiates coverage with a 'Buy' rating.