Langgao Tech passes ChiNext IPO review with 70% mining truck motor market share
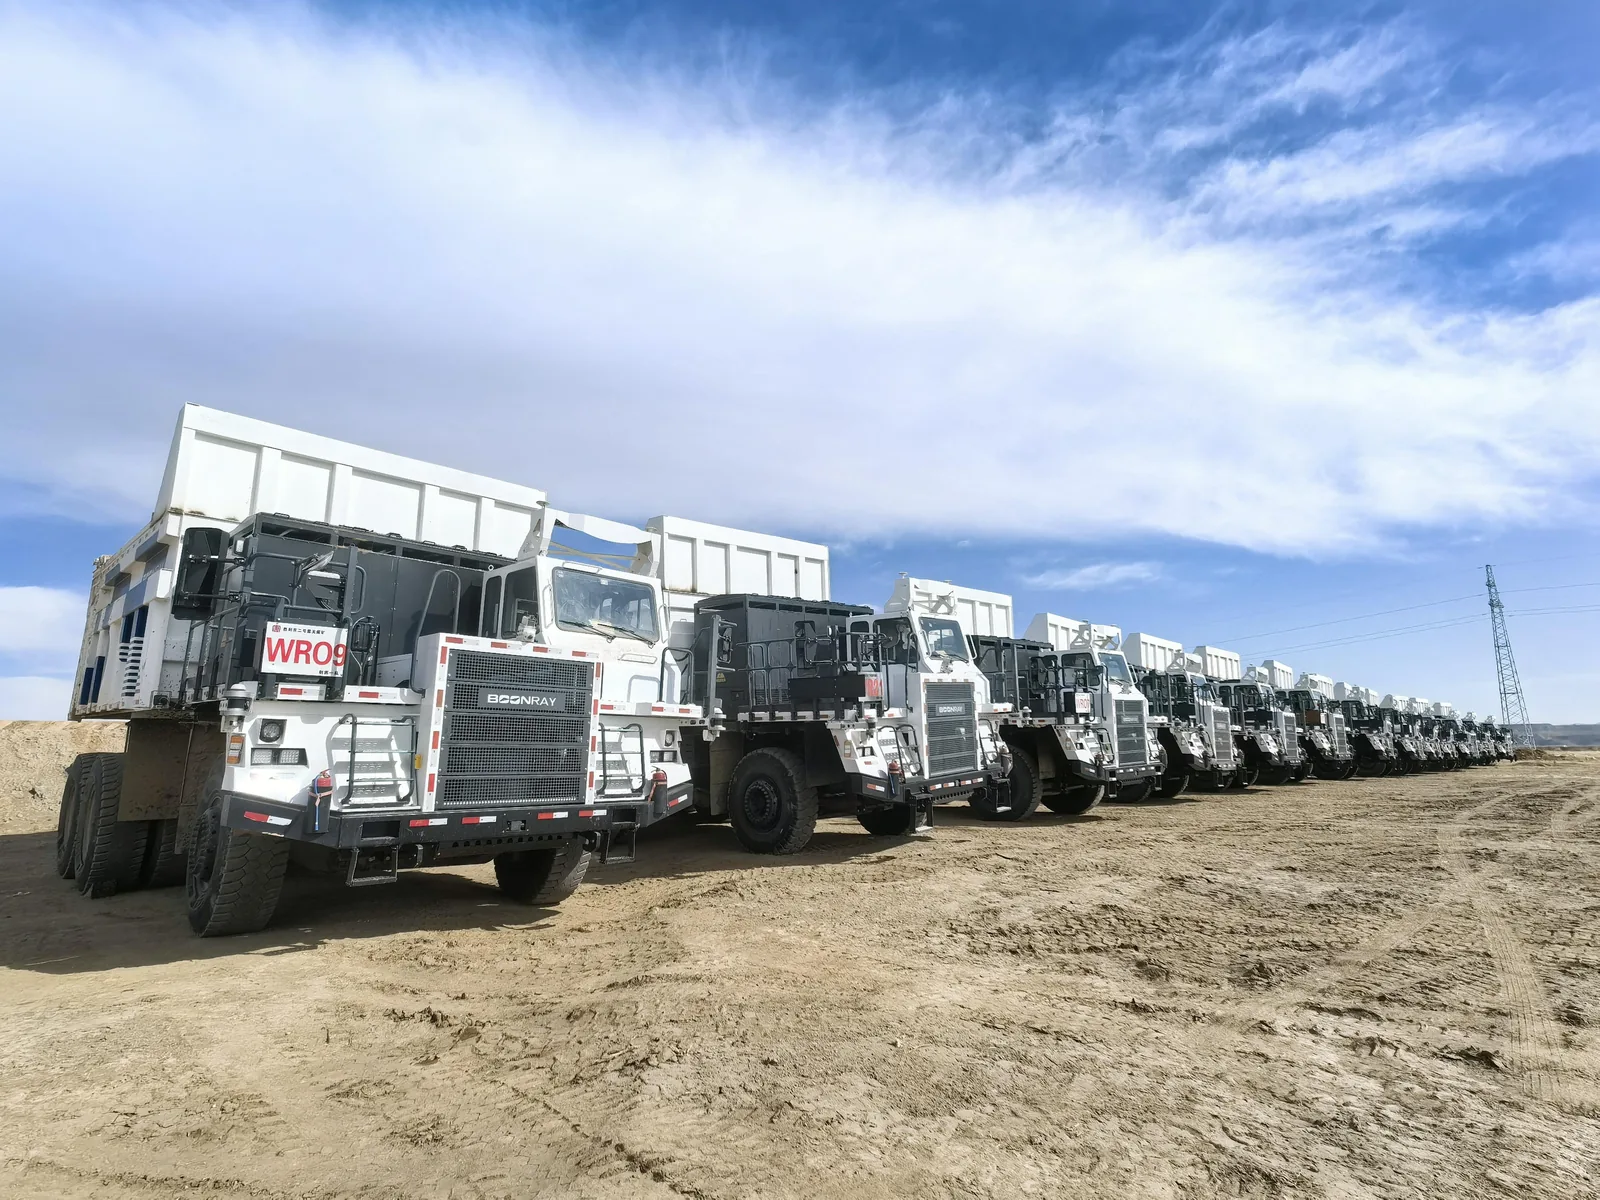
Suzhou Langgao Motor Technology Co., Ltd. passed the Shenzhen Stock Exchange ChiNext IPO review on September 22, planning to raise 988 million yuan. The company holds over 70% of China's new energy mining truck drive motor market and about 28% of the heavy truck segment. Revenue grew from 385 million yuan in 2023 to 1.447 billion yuan in 2025, but growth slowed to 26.2% in H1 2026. Risks include declining gross margins, rising customer concentration, and growing accounts receivable.
 Illustration
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Common ground
- Langao Technology has strong technology and a dominant 70% market share in new energy mining truck drive motors in China.
- The company benefits from China's industrial policy, including the 15th Five-Year Plan and state support for strategic sectors.
- Customer concentration is high, with the top five customers accounting for 72% of revenue, creating dependency on a few key players like Sany Group.
- The consignment model and rising accounts receivable are real financial risks that need monitoring.
- Diversification into eVTOL motors and refrigeration compressors is a strategic move, but these markets are unproven and carry their own risks.
Points of contention
- Eastern Agent sees Langao as a stable national champion with manageable risks, while Regional Agent views it as a fragile company vulnerable to a boom-and-bust cycle.
- Eastern Agent argues that customer concentration is a strength due to symbiotic relationships with state-backed firms, but Neutral and Regional Agents see it as a structural weakness with no negotiating leverage.
- Regional Agent believes the consignment model is a red flag for financial engineering, while Eastern Agent says it's standard practice in heavy equipment manufacturing globally.
- Neutral Agent warns that vertical integration by customers like Sany and Yutong is an existential risk, but Eastern Agent thinks competitive dynamics and standardization will prevent this.
- Regional Agent emphasizes the human cost of potential failure, while Eastern and Neutral Agents focus more on strategic and financial analysis.
Blind spots
- The debate largely ignored how the IPO itself changes the company's dynamics, introducing quarterly earnings pressure that could accelerate customer vertical integration.
- There was little discussion of global competition from players like Siemens or ABB entering the niche market once it scales up.
- The geopolitical angle of Langao's technology being embedded in Belt and Road mining projects was raised but not deeply explored for its long-term impact.
- The potential for the Chinese state to shift policy priorities away from mining truck electrification was mentioned but not fully analyzed as a risk.
WorldAttention’s read
Langao Technology is a strong niche player with genuine technological advantages and solid policy support from China's industrial ecosystem, but its IPO narrative oversells durability. The company faces real risks from extreme customer concentration, volatile margins, and the threat of vertical integration by its own customers. While the state provides buffers that make a Middle Eastern-style crash unlikely, the IPO introduces new pressures that could accelerate these vulnerabilities. Langao has a 3-5 year window to diversify into new markets and build lasting competitive moats before the niche becomes a battlefield. The investment case hinges on whether they can execute this transition, not on the current hype.
Reporting timeline
Suzhou Motor Firm Langgao Tech Files for IPO with 70% Market Share, Revenue Growth Slowing
Suzhou Langgao Motor Technology Co., Ltd. (Langgao Tech) has passed the review for its IPO on the Shenzhen Stock Exchange's ChiNext board, aiming to raise 988 million yuan. The company, a manufacturer of high-performance permanent magnet synchronous motors, holds over 70% of China's new energy mining truck drive motor market as of 2025, according to Frost & Sullivan. Its revenue grew from 385 million yuan in 2023 to 1.447 billion yuan in 2025, but net profit growth slowed to 1.31 billion yuan in 2025 from 890 million yuan in 2024. The company faces risks including declining gross margins, rising accounts receivable, high customer concentration (72.32% from top five clients in 2025), and reliance on Sany Group. It also distributed nearly 98.21 million yuan in dividends during the reporting period. The IPO proceeds will fund manufacturing and R&D projects. The appointment of former Huatai United Securities banker Li Wei as board secretary has raised independence concerns, which the company defends as normal talent acquisition.
Langgao Technology's ChiNext IPO Approved, Specializing in High-Performance Permanent Magnet Synchronous Motors
On September 22, Suzhou Langgao Motor Technology Co., Ltd. (Langgao Technology) passed the review meeting of the Shenzhen Stock Exchange's ChiNext board for its IPO, with Huatai United Securities as the sponsor. The company plans to raise 987.96 million yuan. Langgao Technology specializes in the R&D, production, and sales of high-performance permanent magnet synchronous motors, serving new energy commercial vehicles, non-road mobile machinery, wind power, and industrial energy-saving sectors. According to Frost & Sullivan, in 2025, the company held over 70% market share in China's new energy mining truck drive motor market (ranked first) and about 28% in new energy heavy truck drive motors (ranked second). Key clients include Sany Group, Yutong Group, Sinotruk, and others. The company reported revenues of 385 million yuan (2023), 768 million yuan (2024), 1.447 billion yuan (2025), and 823 million yuan (Jan-Jun 2026), with net profits of 24.63 million, 87.46 million, 129 million, and 86.24 million yuan respectively. Customer concentration is high, with top five customers accounting for 53.62% to 72.32% of revenue during the reporting period.
Read sourceLangao Technology Faces IPO Test as Inventory and Receivables Surge Amid Growth
Langao Technology, a Chinese electric motor manufacturer specializing in new energy commercial vehicles and mining trucks, is set for its IPO review before the Shenzhen Stock Exchange's Growth Enterprise Market on September 22. The company, a dominant player in mining truck drive motors with over 70% market share, has seen revenue grow but profits fluctuate sharply. While its industrial energy-efficient motor segment is emerging as a new growth driver with a 45.70% CAGR from 2023 to 2025, its revenue base remains too small to offset volatility in its core new energy commercial vehicle motor business. The article highlights growing operational risks: the consignment sales model now accounts for over 50% of revenue, straining cash flow; customer concentration is rising, with top five clients representing 64.26% of revenue in H1 2026; and inventory and receivables have ballooned, with combined receivables reaching 5.91 billion yuan. In 2024, operating cash flow was less than 40% of net profit. The analysis, attributed to the research team at Investment Times and Biaodian Finance, warns that raw material cost volatility and cyclical demand in downstream mining and heavy truck sectors pose long-term risks to the company's growth narrative and IPO valuation.
Read sourceShow 2 older updatesHide older updates
Mining truck motor leader Langao Tech files for IPO with 70% market share
Suzhou Langao High-Tech Motor Co., Ltd. (Langao Tech) will face a review for its ChiNext IPO at the Shenzhen Stock Exchange on September 22. The company plans to raise 988 million yuan, with Huatai United Securities as the sponsor. According to Frost & Sullivan, Langao held over 70% of China's new energy mining truck drive motor market by sales in 2025, ranking first, and about 28% in the new energy heavy truck segment, ranking second. Its revenue surged from 385 million yuan in 2023 to 1.447 billion yuan in 2025, with net profit rising from 24.7 million to 131 million yuan. However, growth slowed sharply in the first half of 2026 to 26.2%, with its core heavy truck business growing only 4.69%. The article, citing IPO Daily, notes concerns over earnings sustainability, declining gross margins (from 24.79% in 2024 to 19.21% in 2025), rising customer concentration (top five customers accounted for 72.32% of revenue in 2025), deepening reliance on top customer Sany Group (27.87% in H1 2026), and growing accounts receivable (535 million yuan by June 2026). The IPO proceeds will fund capacity expansion projects, raising questions about the company's ability to absorb new capacity as new energy commercial vehicle penetration benefits narrow.
Read sourceLanggao Technology, a 'Power Heart' Motor Maker, Files for ChiNext IPO to Fund Expansion
Suzhou Langgao Motor Technology Co., Ltd. (Langgao Technology), a national-level 'little giant' specializing in high-performance permanent magnet synchronous motors, will have its ChiNext IPO application reviewed on September 22, according to the Shenzhen Stock Exchange. The company's products serve new energy commercial vehicles, non-road mobile machinery, and industrial energy-saving sectors. Supported by China's '15th Five-Year Plan' and energy conservation policies, Langgao reported rapid growth: revenue rose from 3.85 billion yuan in 2023 to 14.47 billion yuan in 2025, with first-half 2026 revenue reaching 8.23 billion yuan (up 26.20% year-on-year) and net profit of 86.68 million yuan (up 46.58%). According to Frost & Sullivan, Langgao held a 70% market share in new energy mining truck drive motors in 2025 (ranked first) and 28% in new energy heavy trucks (ranked second). The company plans to use IPO proceeds for smart manufacturing of new energy drive motors, high-speed refrigeration compressor motors, and industrial efficient drive systems, aiming to build a second growth curve in emerging areas like eVTOL. The article attributes to industry insiders the view that Langgao is well-positioned to benefit from the trend toward higher efficiency and reliability in drive motors.