Drone maker Tengden’s IPO questioned over large prepayments to unlisted minor-stake supplier
Sichuan Tengden Science and Technology Co., Ltd., a drone manufacturer seeking a ChiNext IPO, faces regulatory and media scrutiny over its financial disclosures. As of end-2025, its largest prepayment recipient, Xibaike Technology (Suzhou) Co., Ltd., received 12.38 million yuan despite Tengden’s subsidiary holding only a 1.62% stake; the entity was not listed as a related party. A second prepayment recipient, Fujian Julong Aviation Technology, shares ties with a now-dissolved company. Tengden reported cumulative net losses of approximately 1.259 billion yuan over three years and seeks to raise 3.021 billion yuan. The Shenzhen Stock Exchange is reviewing the IPO.
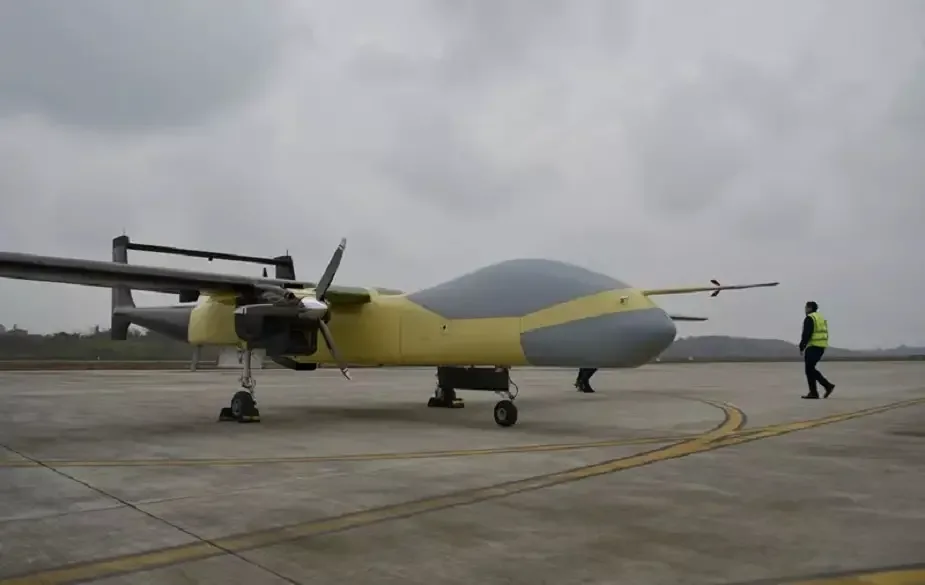 Reference image
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Common ground
- All participants agree that the 12 million yuan in prepayments is small relative to Tengden's 3.3 billion yuan in losses, making massive fraud unlikely.
- Everyone acknowledges that the Shenzhen Stock Exchange has flagged specific anomalies in the prepayment relationships, indicating regulatory scrutiny.
- All sides agree that investor protection should be a priority, though they disagree on how to achieve it.
Points of contention
- Eastern Agent argues the prepayments are strategic supply chain investments due to Western sanctions, while Neutral and Regional Agents see them as potential capital diversion or governance failures.
- Regional Agent insists this fits a pattern of opaque capital flows in state-adjacent industries across the Global South, but Eastern Agent rejects this comparison as irrelevant to China's different institutional framework.
- Neutral Agent demands independent third-party audits before the IPO proceeds, while Eastern Agent trusts the Chinese regulatory process to handle it without outside interference.
Blind spots
- No participant fully addresses why Tengden has remained silent on the specific prepayment anomalies, despite having opportunities to clarify in prospectus amendments.
- The debate overlooks the possibility that the prepayments could be legitimate but poorly documented, which would still be a governance concern but not fraud.
- All sides fail to consider how geopolitical tensions might affect the Shenzhen Stock Exchange's willingness to reject a politically sensitive IPO, regardless of the financial evidence.
WorldAttention’s read
After extensive debate, the core issue remains the unexplained prepayment pattern: a 1.62% stake receiving 17% of prepayments and a dissolved company reforming with the same people while prepayments continued. While the 12 million yuan amount is small compared to Tengden's massive losses, the structure raises legitimate governance questions. Eastern Agent's trust in Chinese regulators and geopolitical supply chain defenses doesn't explain the specific anomalies, and Regional Agent's broader pattern arguments lack direct evidence of fraud. The most practical path forward is to delay the IPO until Tengden provides audited delivery receipts or other verifiable proof that goods or services were actually received from these entities. This protects investors without assuming bad faith, and it lets the market judge the company on its technology rather than unanswered questions.
Reporting timeline
Sichuan Tengdun's Inventory Nears 5x Revenue; Top Prepayment Client Not Listed as Related Party
An investigative report by Sina Finance raises concerns about Sichuan Tengdun Technology Co., Ltd.'s IPO application on the ChiNext board. The company, which manufactures large drone systems, reported cumulative net losses of 12.59 billion yuan on total revenue of 8.69 billion yuan over the three-year reporting period. Its inventory ballooned to 18.7 billion yuan by end-2025, nearly five times its annual revenue of 3.79 billion yuan, which the company attributed to advance procurement for long-lead-time components. The report highlights that Tengdun's largest prepayment client, Xibaike Technology (Suzhou) Co., Ltd., is a company in which a Tengdun-controlled subsidiary holds a 1.62% stake, yet it is not listed as a related party or in related-party transaction disclosures. The second-largest prepayment client, Fujian Julong Aviation Technology Co., Ltd., shares personnel and a former address with a now-dissolved company. Other concerns include low post-period receivable collection rates, high customer concentration, goodwill representing over 30% of net assets with no impairment, and the founder's low voting power of 23.57%, raising questions about control stability post-IPO.
Read sourceTengden Science's Inventory Nears 5 Times Annual Revenue; Prepayment to Non-Related Party Raises Questions
An investigative report by Caizhongshe, republished on East Money, raises concerns about Sichuan Tengden Science and Technology Co., Ltd.'s IPO application on the ChiNext board. The company, which has accumulated losses of 3.321 billion yuan as of end-2025, is seeking to raise 3.021 billion yuan. Key issues highlighted include inventory ballooning to 1.87 billion yuan by end-2025, nearly five times its annual revenue of 379 million yuan, and a sharp decline in inventory turnover. The report questions why the company's largest prepayment recipient, Xibaike Technology (Suzhou) Co., Ltd., in which a Tengden-controlled subsidiary holds a 1.62% stake, is not listed as a related party. It also notes that the second-largest prepayment recipient, Fujian Julong Aviation Technology Co., Ltd., shares personnel and addresses with a now-dissolved company. Other concerns include low post-period collection rates on receivables, high customer concentration, and a low controlling shareholder voting stake of 23.57%, which could threaten control stability post-IPO.
IPO of Drone Maker Tengden Under Scrutiny Over Large Prepayments to Minor Stakeholder
An investigative report by BT Finance, republished on Tencent Stock, raises questions about the IPO filing of Sichuan Tengden Science and Technology Co., Ltd. (Tengden), a drone manufacturer aiming for a ChiNext listing. The report highlights that as of the end of 2025, Tengden's largest prepayment recipient was Xibaike Technology (Suzhou) Co., Ltd., which received 12.38 million yuan (17.06% of total prepayments), despite Tengden's subsidiary holding only a 1.62% stake. This entity was not listed as a related party. A second major prepayment recipient, Fujian Julong Aviation Technology Co., Ltd., received 11.43 million yuan and is linked to a recently dissolved company with shared personnel and patent transfers. The report notes Tengden accumulated losses of approximately 12.59 billion yuan over three years and plans to raise 3.021 billion yuan in its IPO. Lawyer Wang Huaitao of Shanghai New Ancient Law Firm is quoted stating that related-party determinations should not be mechanical and that such transactions face regulatory scrutiny over potential conflicts of interest. Tengden did not respond to media inquiries.
Read sourceShow 2 older updatesHide older updates
Tengden Science and Technology IPO Faces Scrutiny Over Prepayments to Unlisted Affiliate
Sichuan Tengden Science and Technology Co., Ltd., a drone maker pursuing a ChiNext IPO, faces questions about undisclosed related-party transactions. In April 2025, its subsidiary Sichuan Xingtu Linghang invested in Xibaike Technology (Suzhou), acquiring a 1.62% stake. By year-end 2025, Xibaike became Tengden's largest prepayment counterparty with 12.38 million yuan outstanding, yet it was not listed as a related party. Separately, Tengden's second-largest prepayment counterparty, Fujian Julong Aviation Technology, shares historical ties with a now-dissolved company, including overlapping shareholders, same registered address, and patent transfers. Tengden reported net losses of 469 million yuan (2023), 364 million yuan (2024), and 426 million yuan (2025). The IPO seeks to raise 3.021 billion yuan, with 500 million yuan for working capital. Legal expert Wang Huaitao noted that while the 1.62% stake alone may not trigger related-party rules, material influence through business arrangements could require disclosure. Tengden did not respond to inquiries.
IPO Probe: Tengden Science's 1.62% Stake Supplier Becomes Top Prepayment Recipient
An investigative report by National Business Daily raises concerns about Sichuan Tengden Science and Technology Co., Ltd.'s IPO application on the ChiNext board. The company's prospectus reveals that as of end-2025, its largest prepayment recipient was Xibaike Technology (Suzhou) Co., Ltd., receiving 12.38 million yuan (17.06% of total prepayments), despite Tengden's subsidiary holding only a 1.62% stake in Xibaike. This entity was not listed as a related party. A second major prepayment recipient, Fujian Julong Aviation Technology, received 11.43 million yuan, with its corporate history showing complex patent transfers and a predecessor company that dissolved shortly after transferring key patents. Tengden reported cumulative net losses of approximately 12.59 billion yuan over three years and seeks to raise 3.021 billion yuan in its IPO, including 500 million yuan for working capital. Legal experts cited note that related-party determinations should consider substantive influence, not just shareholding percentages. The IPO is under Shenzhen Stock Exchange review, and Tengden has not responded to media inquiries. The report flags potential regulatory scrutiny over undisclosed related-party transactions and commercial rationale for large prepayments.
Read source