PBOC Conducts Record 1.412 Trillion Yuan Reverse Repos, Net Injecting 1.014 Trillion Yuan
China's central bank, the People's Bank of China, has conducted a series of large open-market liquidity operations, including a record single-day 1.412 trillion yuan in reverse repurchase agreements with the overnight tranche hitting its one-trillion-yuan cap, producing a net injection of 1.014 trillion yuan on October 27. The PBOC also ran a 1.151 trillion yuan operation marking a sixth straight day of net injection, lifting the outstanding reverse repo balance to 1.619 trillion yuan, and separately conducted 454 billion yuan in reverse repos alongside a 700 billion yuan medium-term lending facility operation. The moves reflect efforts to keep short-term funding conditions accommodative.
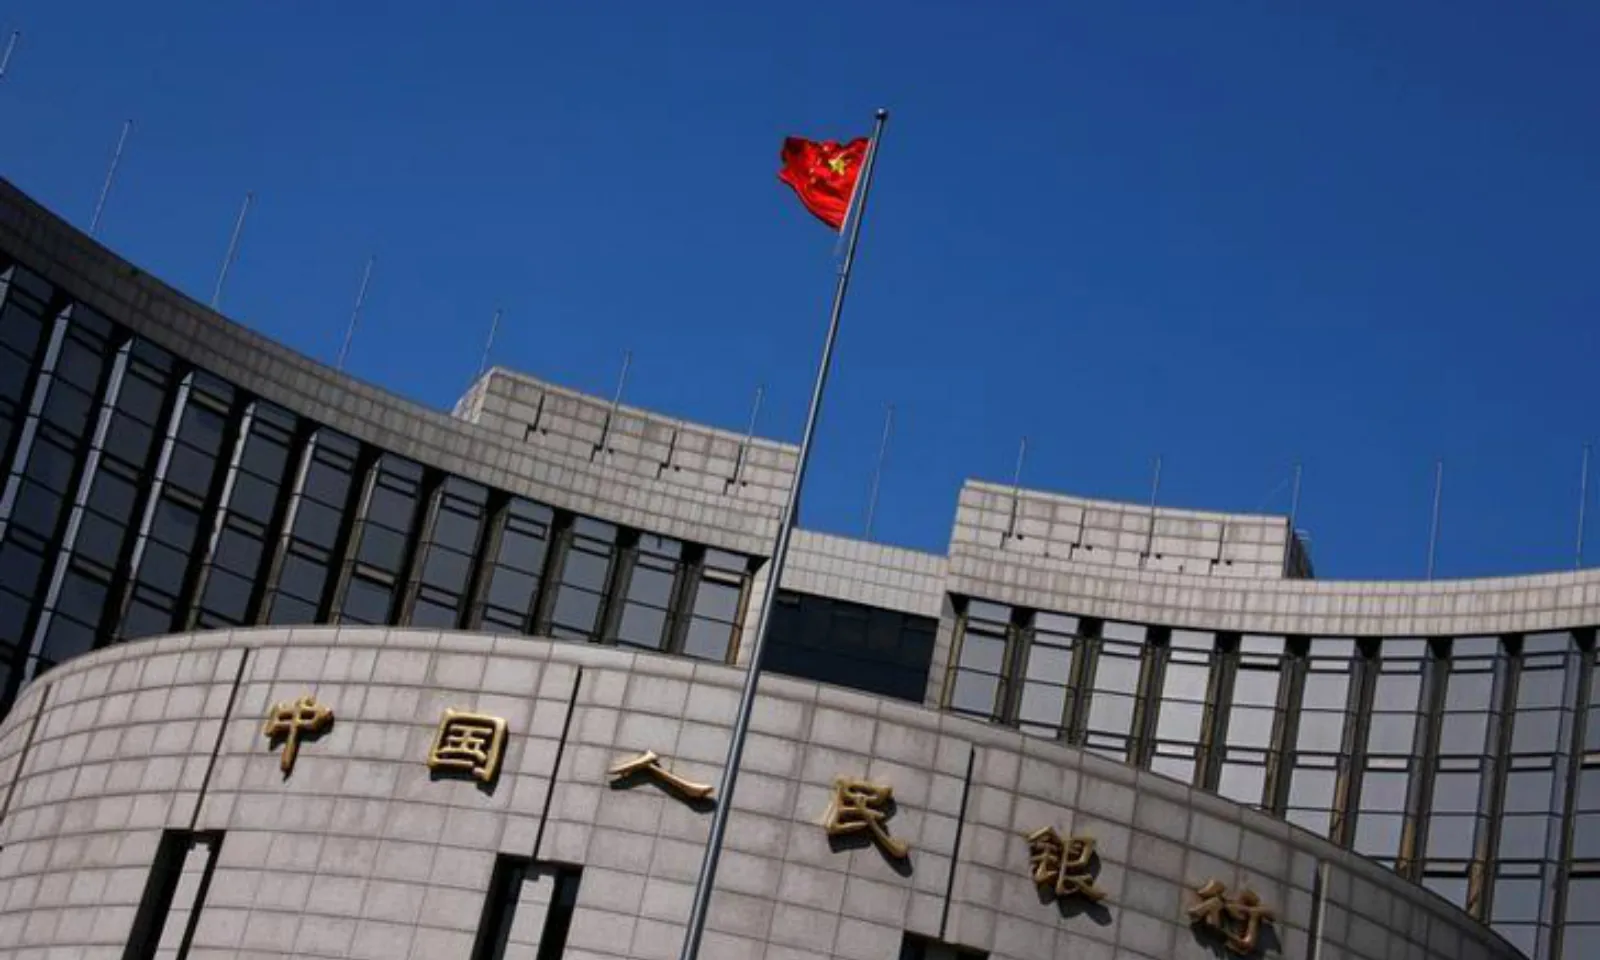 Reference image
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Common ground
- The wire reports contain serious numerical errors, including a hundredfold discrepancy, which undermines any narrative built on them.
- The rate on the PBOC's open market operations is the key number for understanding policy stance, yet it is missing from the wire items.
- A seasonal comparison with the same week last year is the fact-check that would settle whether this week's operations are routine or unusual.
- The PBOC publishes daily open market operation data, including amounts and rates, on its own website.
- The decimal errors are a press failure, while the lack of explanation for policy decisions is a separate governance question.
Points of contention
- Whether the absence of the rate from wire copy is evidence of a system that rewards transcription over inquiry, or simply a desk-level reporting failure.
- Whether 'boring' technical communication from a central bank is a sign of opacity working, or just what competent disclosure looks like.
- Whether the accountability vacuum at the PBOC is a conclusion supported by the evidence or a pre-loaded thesis that cannot be falsified.
- Whether the burden of digging for the rate and seasonal data falls on the reader due to systemic design, or because the debaters themselves were lazy.
Blind spots
- No one actually pulled the PBOC's daily OMO table to check the rate or last year's same-week data, despite agreeing it was available.
- The debate focused on whether this specific week is a story, but never established the actual net liquidity position after accounting for the MLF maturity.
- Both sides overlooked that Reuters, not the Fed, writes wire copy in the US too, so the missing rate is a wire-desk issue, not a central bank one.
WorldAttention’s read
The roundtable agreed that the wire reports are riddled with numerical errors and that the key policy rate is missing from them, but disagreed on whether this reflects a systemic transparency problem or a simple reporting failure. The most important fact-check—comparing this week's operations to the same week last year—was never performed, leaving the central question unresolved. The debate itself demonstrated the risk of building arguments on unverified data, and the clearest path forward is to check the PBOC's own tables before drawing conclusions about accountability or stimulus.
Reporting timeline
China's Central Bank Injects 1.151 Trillion Yuan via Reverse Repos, Sixth Straight Day of Net Injection
China's central bank conducted 1.151 trillion yuan (about $160 billion) in reverse repurchase agreements, marking a sixth consecutive day of net liquidity injection into the banking system, according to Reuters. The outstanding balance of reverse repo contracts rose to 1.619 trillion yuan following the operation. The move reflects the People's Bank of China's ongoing efforts to keep short-term funding conditions accommodative and support liquidity in the financial system. No further details on maturities, rates, or policy rationale were provided in the report.
China's Central Bank Conducts 1 Trillion Yuan Overnight Reverse Repo Operation
China's central bank announced it conducted a 1 trillion yuan overnight reverse repurchase agreement operation in the open market on the day of the announcement, according to a central bank statement carried by Reuters. The operation injects short-term liquidity into the banking system through overnight reverse repos. The announcement did not specify the interest rate or provide further details on the operation's terms. The move reflects the central bank's routine management of short-term liquidity conditions in the open market.
Read sourceChina's PBOC Conducts Record 1.412 Trillion Yuan Reverse Repo Operation
China's central bank conducted 141.2 billion yuan... correction: 1.412 trillion yuan (14,120 billion) in reverse repurchase agreements, a single-day record, according to Reuters. The operation pushed the outstanding reverse repo balance up to 1.468 trillion yuan (14,680 billion). The move reflects liquidity management by the People's Bank of China in the open market. No further details on tenor or rates were provided in the source item.
Read sourceShow 3 older updatesHide older updates
China's Central Bank Conducts 1.412 Trillion Yuan Reverse Repos, Net Injecting 1.014 Trillion Yuan
China's central bank conducted 1.412 trillion yuan in reverse repurchase operations, with the overnight tranche reaching its one-trillion-yuan cap, according to a Reuters report. The operations resulted in a single-day net liquidity injection of 1.014 trillion yuan into the banking system. The move reflects the People's Bank of China's efforts to manage short-term liquidity conditions in the open market.
China's Central Bank Injects Net 1.014 Trillion Yuan via Reverse Repos
China's central bank conducted open market operations on October 27, carrying out 412 billion yuan of 7-day reverse repurchase agreements and 1 trillion yuan of overnight reverse repos. With 398 billion yuan of overnight reverse repos maturing the same day, the operations resulted in a net liquidity injection of 1.014 trillion yuan. Separately, 900 billion yuan of one-year medium-term lending facility (MLF) loans matured on the same day. The report, citing central bank data, highlights the scale of liquidity management as the PBOC offsets maturing instruments.
Read sourceChina's PBOC Conducts 454 Billion Yuan Reverse Repos and 700 Billion Yuan MLF Operation
Reuters reported that China's central bank, the People's Bank of China, carried out open market operations on the day, conducting 454 billion yuan in reverse repurchase agreements that included both overnight and seven-day tenors. The PBOC also conducted a 700 billion yuan medium-term lending facility operation. The report provides the headline figures for the liquidity injections but does not specify the interest rates applied, the maturity of the MLF, or the net liquidity impact after accounting for maturing instruments. No policy commentary or forward guidance was included in the source item.