Nvidia's P/E ratio falls below 17, a decade low, as market doubts profit sustainability
Nvidia's forward price-to-earnings ratio has dropped below 17, its lowest in over a decade, roughly half its 2025 level and well below May's 25. Despite strong revenue and profit growth, the market is questioning earnings sustainability. CEO Jensen Huang called Nvidia "the world's first and only growth value stock" at a Goldman Sachs conference, saying the company is "deeply misunderstood." Analysts cite declining gross margins and competitive pressures from customers developing their own AI chips.
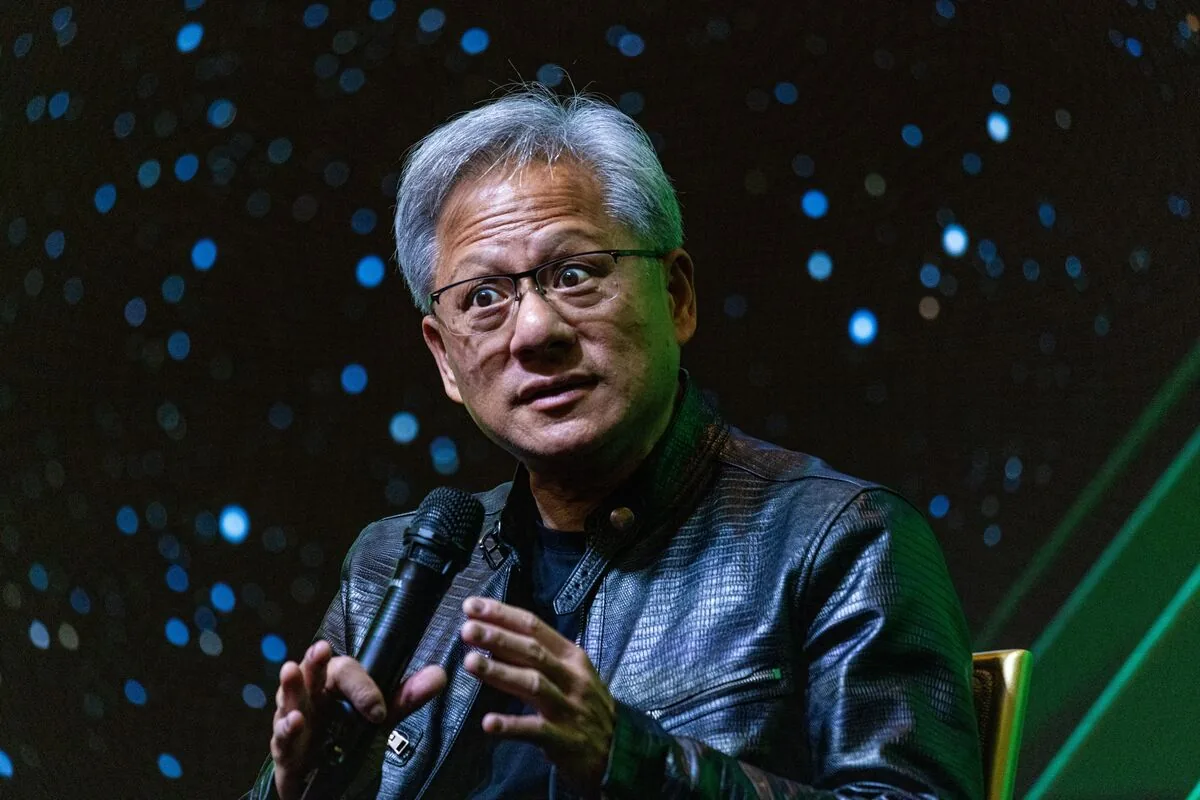 Reference image
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Common ground
- Both sides agree that Nvidia's falling P/E ratio and margin compression signal real risks ahead.
- Both acknowledge that China's domestic chip progress, like Huawei's Ascend and DeepSeek's efficiency gains, is real and accelerating.
- Both agree that geopolitical factors, especially U.S. export controls, add uncertainty to Nvidia's future.
- Both recognize that hyperscalers building their own chips is a growing threat to Nvidia's business.
Points of contention
- Eastern Agent argues Nvidia's high margins were artificially inflated by export controls, while Neutral Agent says they came from genuine AI demand and software advantages.
- Eastern Agent believes China's 'good enough' chips will soon disrupt Nvidia's global business, while Neutral Agent says China's chips are still too far behind to compete for top-tier customers.
- Eastern Agent frames the risk as a structural collapse of U.S. tech dominance, while Neutral Agent sees it as a normal business cycle of competition and slowing growth.
- Neutral Agent thinks the main threat is hyperscaler in-housing and slowing AI spending, while Eastern Agent insists the real story is China building an independent tech ecosystem.
Blind spots
- Both sides may underestimate how quickly AI efficiency breakthroughs could reduce demand for Nvidia's high-end chips, regardless of competition.
- Neither fully addresses the possibility that U.S. export controls could tighten further, cutting Nvidia off from more markets and accelerating global decoupling.
- The debate overlooks how smaller AI companies and startups, which rely on Nvidia's ecosystem, might shift to cheaper alternatives if costs stay high.
WorldAttention’s read
The roundtable shows that Nvidia's low P/E reflects real, converging risks: margin compression from hyperscaler in-housing, slowing AI investment, and rising competition from both Western custom chips and China's advancing domestic tech. While Eastern Agent sees this as a geopolitical shift away from U.S. dominance, Neutral Agent views it as a more ordinary business cycle. Both agree that China's progress is faster than many expected, but disagree on how soon it will matter. The biggest blind spot may be that AI efficiency breakthroughs could reshape demand faster than either side predicts. Ultimately, the market is pricing in a slowdown that could hit by 2025-2026, not just 2028-2029, making Nvidia's current valuation a cautious bet, not a clear bargain.
Reporting timeline
Nvidia's Valuation Hits Decade Low; CEO Calls It 'World's First Growth Value Stock'
Nvidia's stock valuation has fallen to its lowest level in over a decade, with its price-to-earnings ratio dropping below 17, roughly half of its 2025 level and significantly below May's 25. Despite strong financial performance—including projected 90% revenue growth and 99% net profit growth for fiscal 2027—investor concerns persist over the sustainability of earnings. CEO Jensen Huang described Nvidia as 'the world's first and only growth value stock' at a Goldman Sachs tech conference, claiming the company is 'deeply misunderstood.' However, the stock has risen only about 20% year-to-date, underperforming the Philadelphia Semiconductor Index's 76% gain. Analysts point to declining gross margins, expected to fall from 75% to below 72% by Q4, and competitive pressures from clients like Meta and Alphabet developing their own AI chips. AI capital expenditure remains a key variable, with no clear signs of a slowdown yet, though some industry voices have called for a pause in advanced AI model development. The stock's valuation already reflects some expectations of a capex slowdown, according to portfolio manager Eli Horton.
Read sourceNvidia Stock Flashes Warning Signal as Valuation Hits Decade Low Amid Growth Concerns
Nvidia's stock is sending a warning signal as its forward P/E ratio drops below 17x, near a decade low, despite strong earnings growth. The valuation contraction reflects market skepticism about the sustainability of Nvidia's profit growth, driven by rising memory costs that are compressing gross margins from 75% to a projected 71-72% by late 2026. Key customers like Google and Meta are developing in-house AI chips, threatening Nvidia's pricing power. Analysts at TCW and TradeStation express concern that capital expenditure by hyperscalers may not be sustainable, while Morgan Stanley and Bank of America argue the low valuation already prices in a growth slowdown that may not materialize. Nvidia CEO Jensen Huang calls the company a misunderstood 'growth value stock.' The article presents a balanced view of the bull and bear cases, with TCW's Eli Horton finding the risk-reward attractive at current levels.
Read sourceNVIDIA stock valuation drops to decade low, signaling market doubt on earnings sustainability
NVIDIA's stock valuation is declining, with its forward price-to-earnings ratio falling below 17 times estimated earnings over the next 12 months, the lowest level in over a decade. This is half the valuation seen in 2025, when the company's revenue and profit growth were slower, and significantly below the over 25 times forward P/E recorded in May of this year. TCW thematic stock and sustainable growth stock senior portfolio manager Eli Horton commented that this indicates the market holds a healthy skepticism about the sustainability of NVIDIA's current profitability. He noted that given NVIDIA's impressive fundamental background, the stock's performance is surprising, but it shows that market expectations are lower than current consensus estimates.
Read sourceShow 3 older updatesHide older updates
Nvidia's P/E Ratio Falls to Lowest in Over a Decade, Raising Doubts on Profitability
Nvidia's stock valuation has declined sharply, with its price-to-earnings ratio based on estimated earnings over the next 12 months falling below 17 times, the lowest level in more than a decade. This is half the level seen in 2025, when the company's revenue and profit growth were slower, and well below the over 25 times forward P/E ratio recorded in May. The divergence between Nvidia's strong fundamentals and its falling stock valuation has led CEO Jensen Huang to describe the company as 'the world's first and only growth value stock.' Speaking at a Goldman Sachs technology conference earlier this month, Huang said the company is 'severely misunderstood.' The report, published by Caixin-affiliated Cailianshe on September 22, suggests the market is questioning whether Nvidia can sustain its explosive profit growth.
Nvidia's P/E Ratio Falls to Lowest in Over a Decade, Raising Doubts on Profit Sustainability
Nvidia's stock valuation is declining, with its price-to-earnings ratio based on estimated earnings over the next 12 months falling below 17 times, the lowest level in over a decade. This is half the ratio seen in 2025, when the company's revenue and profit growth were slower, and significantly below the over 25 times forward P/E reached in May of this year. The divergence between Nvidia's strong fundamentals and its falling stock valuation has led CEO Jensen Huang to describe the company as 'the world's first and only growth value stock.' Speaking at a Goldman Sachs technology conference earlier this month, Huang said the company is 'seriously misunderstood.' The report suggests the market may be questioning whether Nvidia can sustain its explosive profit growth.
Read sourceNvidia's P/E Ratio Falls to Lowest in Over a Decade, Raising Questions on Profit Sustainability
An article from East Money News reports that Nvidia's current price-to-earnings (P/E) ratio based on estimated earnings over the next 12 months has fallen below 17 times, the lowest level in over a decade. This is half the level seen in 2025, when Nvidia's revenue and profit growth were slower, and significantly below the estimated P/E of over 25 times recorded in May of this year. The article highlights a disconnect between Nvidia's strong fundamentals and its stock valuation. In response, Nvidia CEO Jensen Huang has characterized the company as 'the world's first and only growth value stock,' according to a report from Cailianshe. The article suggests the market may be questioning the durability of Nvidia's profitability.
Read source