Megmeet to acquire full control of welding unit for 664 million yuan amid high receivables ratio
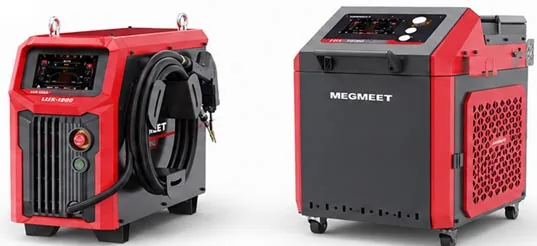
Chinese electrical automation firm Megmeet announced on September 22, 2026, a plan to acquire the remaining 46.30% stake in its subsidiary Shenzhen Megmeet Welding Technology for approximately 664 million yuan in cash, making it a wholly owned subsidiary. The deal values the welding unit at about 1.456 billion yuan, a 501.50% premium over net assets. As of June 30, 2026, Shenzhen Welding's total receivables of 273 million yuan accounted for nearly 70% of its total assets of 390 million yuan. The transaction features a dual-track pricing mechanism with performance commitments for 2026-2028.
 Illustration
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Common ground
- The deal's fairness hinges on the subsidiary's current operating cash flow, which is not publicly available.
- The 70% receivables ratio is a notable risk factor that requires monitoring.
- The sellers' acceptance of a three-year earnout suggests they believe in the business's growth potential.
- The 10.6x forward P/E is reasonable if the profit targets are achievable.
Points of contention
- Eastern Agent sees the deal as a strategic industrial sovereignty play, while Regional Agent views it as a predatory financial scheme.
- Eastern Agent argues the 70% receivables ratio is normal for China's industrial ecosystem, but Neutral and Regional Agents see it as a structural weakness.
- Regional Agent claims the deal transfers risk from capital to labor, while Eastern Agent insists it's a necessary consolidation for global competition.
- Neutral Agent focuses on financial metrics, while Regional Agent emphasizes power imbalances and human costs.
Blind spots
- No one has provided the subsidiary's current operating cash flow, which is key to judging the deal's fairness.
- The debate overlooks the collectibility of the 70% receivables and whether they are tied to risky Belt and Road projects.
- The long-term impact on employees and suppliers if the profit targets are not met is not addressed with concrete data.
- The role of China's regulatory oversight (CSRC) in protecting minority shareholders is assumed but not verified.
WorldAttention’s read
This deal is a moderately priced take-private of a subsidiary with a high-receivables balance sheet and a plausible growth story. The 10.6x forward P/E is fair if the 135 million annual profit target is achievable, but the 70% receivables ratio is a yellow flag that needs monitoring. The sellers' willingness to accept a three-year earnout suggests confidence in growth, but the lack of transparency on current cash flow and the collectibility of receivables leaves the deal's true fairness uncertain. Neither the 'industrial champion' narrative nor the 'predatory scheme' narrative is fully supported by available data. The only honest conclusion is that we lack enough information to judge definitively, and anyone claiming certainty is selling a story.
Reporting timeline
Megmeet to Buy Out Welding Unit for $664M, Receivables at 70% of Assets
Chinese electrical automation company Megmeet announced plans to acquire the remaining 46.30% stake in its subsidiary Shenzhen Megmeet Welding Technology for approximately 664 million yuan in cash, taking full ownership. The deal values the welding unit at 14.56 billion yuan, with a static P/E ratio of about 16 times based on 2025 net profit of 88.49 million yuan. However, the subsidiary's financial health raises concerns: as of June 30, 2026, its total receivables stood at 273 million yuan, accounting for nearly 70% of total assets of 390 million yuan. The transaction features a dual-track pricing mechanism: performance-committing sellers will receive up to 640 million yuan based on 2026-2028 profit targets (cumulative net profit of at least 405 million yuan), while two non-committing sellers will receive 24.46 million yuan at 70% of assessed value. Payment is structured in four tranches, with the first 128 million yuan due within 10 days of signing without performance conditions. The company did not respond to inquiries about the high receivables ratio or the adequacy of guarantees from the 44 individual and one employee-shareholding-platform sellers.
Read sourceMegmeet to Buy Out Welding Subsidiary for $664M Amid High Receivables Ratio
Chinese electrical automation firm Megmeet (Shenzhen Megmeet Welding Technology Co., Ltd.) announced a plan to acquire the remaining 46.30% minority stake in its subsidiary Shenzhen Welding for approximately 664 million yuan in cash, achieving full ownership. The deal, disclosed on September 22, 2026, values Shenzhen Welding at about 1.456 billion yuan, reflecting a 501.50% premium over net assets. Notably, as of June 30, 2026, Shenzhen Welding's total receivables stood at 273 million yuan, accounting for nearly 70% of its total assets of 390 million yuan. The transaction features a dual pricing mechanism: performance-committing sellers will receive up to 640 million yuan tied to net profit targets of 105 million yuan (2026), 130 million yuan (2027), and 170 million yuan (2028), or a cumulative 405 million yuan; two non-committing sellers will receive only 70% of their equity's appraised value, or 24.46 million yuan. Payment to committing sellers is structured in four tranches, with the first installment of 128 million yuan (after tax) due within 10 days of signing, without performance conditions. The company did not respond to inquiries from the reporter regarding the high receivables ratio and the financial safeguards for minority shareholders.
Read sourceMegmeet to Buy Out Welding Unit for $664M; Receivables Near 70% of Assets
Chinese power electronics firm Megmeet Electric (Shenzhen) Co., Ltd. plans to acquire the remaining 46.30% stake in its subsidiary Shenzhen Megmeet Welding Technology Co., Ltd. (Shenzhen Welding) for a total valuation of 14.56 billion yuan (approx. $6.64 billion). The deal will make Shenzhen Welding a wholly owned subsidiary. According to the company's announcement, as of June 30, 2026, Shenzhen Welding's total receivables stood at 2.73 billion yuan, accounting for nearly 70% of its total assets of 3.90 billion yuan. The acquisition uses a dual pricing mechanism: performance-committing sellers will receive up to 6.40 billion yuan based on earnings targets for 2026-2028 (cumulative net profit of at least 4.05 billion yuan), while two non-committing sellers will receive 70% of their equity's assessed value, totaling 24.46 million yuan. Megmeet will pay the performance-committing sellers in four installments, with the first payment of 1.28 billion yuan due within 10 days of signing, without any performance review. The article notes that the static price-to-earnings ratio for Shenzhen Welding is about 16 times based on its 2025 net profit of 88.49 million yuan. The company did not respond to inquiries about the high receivables ratio or the guarantee arrangements for the performance commitment.
Read sourceShow 3 older updatesHide older updates
Megmeet to Acquire 46.30% Stake in Shenzhen Welding Subsidiary for 664 Million Yuan
On September 22, Shenzhen-listed Megmeet Electric (002851.SZ) announced it will acquire the remaining 46.30% equity in its controlled subsidiary, Shenzhen Megmeet Welding Technology Co., Ltd., for 664 million yuan in cash. The transaction includes a performance commitment period from 2026 to 2028, during which Shenzhen Welding's cumulative net profit attributable to the parent (excluding non-recurring gains/losses) must reach no less than 405 million yuan. Upon completion, Shenzhen Welding will become a wholly owned subsidiary of Megmeet.
Read sourceMegmeet to Acquire Remaining 46.30% Stake in Shenzhen Welding Subsidiary for 664 Million Yuan
On September 22, Shenzhen-listed Megmeet (002851) announced it will acquire the remaining 46.30% equity interest in its controlled subsidiary, Shenzhen Megmeet Welding Technology Co., Ltd., for 664 million yuan in cash. The transaction includes a performance commitment: the subsidiary's cumulative net profit attributable to the parent (excluding non-recurring gains/losses) for the 2026-2028 period must reach at least 405 million yuan. Upon completion, Shenzhen Welding will become a wholly owned subsidiary of Megmeet. The announcement was reported by the National Business Daily via Tonghuashun Finance.
Read sourceMegmeet to Acquire 46.3% Stake in Shenzhen Welding Subsidiary for 663.6 Million Yuan
On September 22, 2026, Shenzhen Megmeet Electrical Co., Ltd. (002851.SZ) announced a plan to acquire a 46.30% equity stake in its controlled subsidiary, Shenzhen Megmeet Welding Technology Co., Ltd., from 46 minority shareholders for 663.6448 million yuan in cash. The transaction, executed via a cash purchase agreement signed on the same date, aims to enhance the company's operational decision-making efficiency, strengthen control over the welding subsidiary, and improve profitability and core competitiveness. Upon completion, Megmeet will hold 100% ownership of Shenzhen Welding. The acquisition will be funded by the company's own capital.
Read source