Mech-Mind Robotics posts 54.7% revenue growth in first post-IPO half-year results
Mech-Mind Robotics (09615.HK) reported H1 2026 revenue of RMB 237.3 million, up 54.7% year-on-year, with gross margin improving to 65.0%. New orders surged 75.3% to RMB 335.4 million. The company listed on the Hong Kong Stock Exchange on September 1, 2026, with a 3,835x oversubscribed IPO, but shares traded 20% below the issue price by September 21. Adjusted net loss narrowed to RMB 52.5 million despite R&D spending rising 72.9% to RMB 80.1 million.
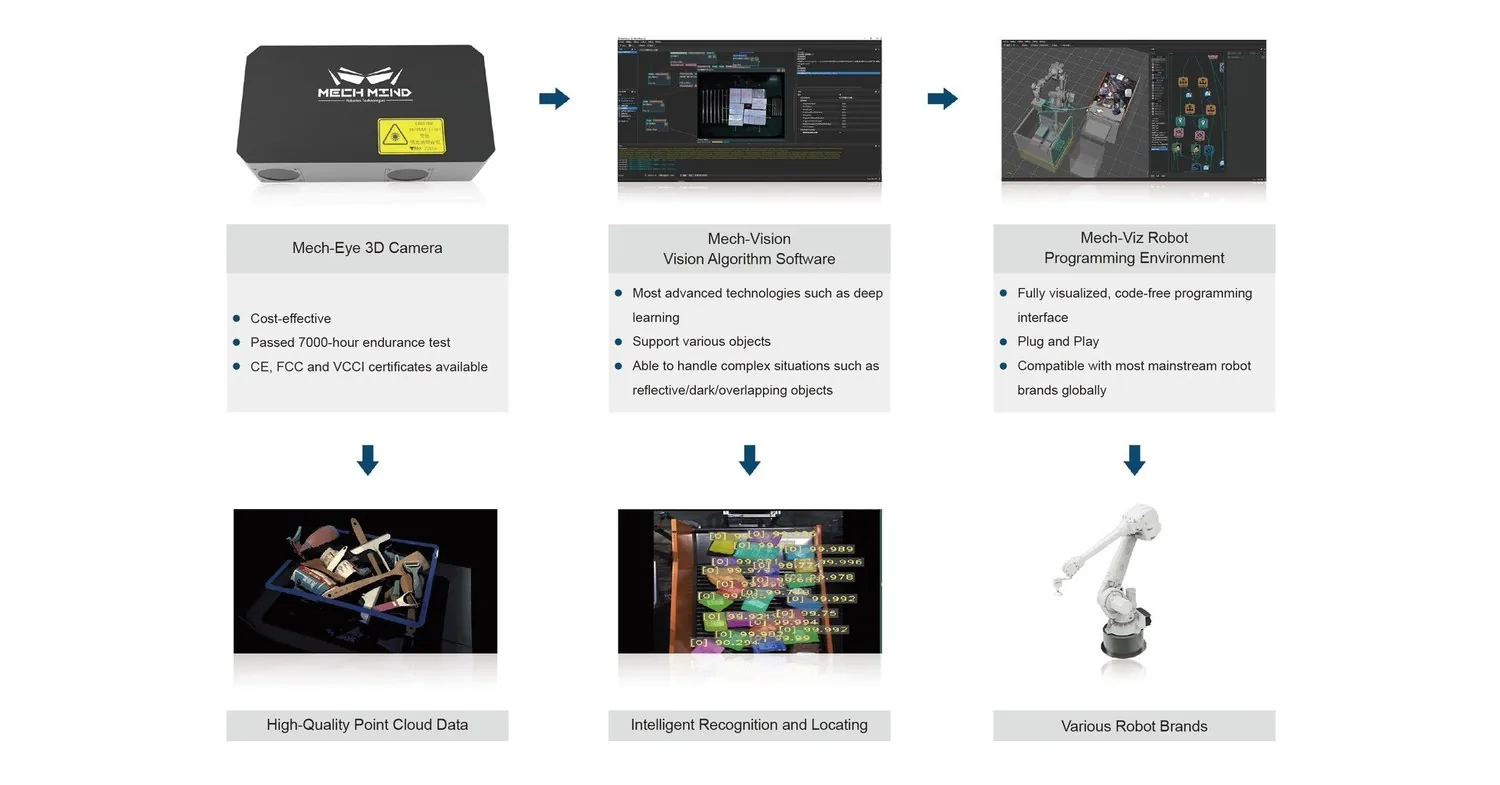 Reference image
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Common ground
- Mech-Mind has real technology and strong commercial traction, with 22% global market share in AI-guided robotics and 65% gross margins.
- The company's overseas revenue, especially 86.5% from developed markets like Europe, the US, Japan, and South Korea, shows genuine demand from global manufacturers.
- The 75.3% growth in new orders indicates strong market interest, though it's not yet converted to revenue.
- The ecosystem lock-in from working with 40+ robot brands creates real switching costs for customers.
Points of contention
- Eastern Agent sees the 30x price-to-sales ratio as justified by market growth and strategic position, while Neutral Agent calls it a terrible entry price for a company that's never turned a profit.
- Eastern Agent views the 20% stock drop as short-term noise, but Neutral Agent sees it as the market correctly pricing in execution risk.
- Regional Agent argues the technology displaces workers and exploits global wage gaps, while Eastern Agent says it creates high-skilled jobs and boosts productivity.
- Neutral Agent warns that orders can be cancelled or discounted, but Eastern Agent insists the 65% gross margins prove customers are paying premium prices.
Blind spots
- No one fully addressed how geopolitical risks like EU 'digital sovereignty' initiatives could directly impact Mech-Mind's overseas revenue.
- The debate lacked concrete data on order-to-revenue conversion rates and whether discounting is happening to win those orders.
- The human impact on workers in developing countries, especially without strong labor protections, was raised but not deeply analyzed with evidence.
WorldAttention’s read
Mech-Mind is a genuinely innovative Chinese robotics company with proven commercial success in global markets, but the debate reveals deep divides over its valuation, the social costs of automation, and the risks of geopolitical backlash. The technology and market traction are real, but whether the stock is a good investment depends on whether you believe the high growth will continue without margin compression or political disruption. The biggest unanswered question is how the benefits of this automation will be shared—whether it lifts workers or leaves them behind—and that depends on policies and market dynamics that go far beyond the company's own performance.
Reporting timeline
Mech-Mind Reports 54.7% Revenue Growth in H1 2026, Physical AI Platform Gains Traction
Mech-Mind Robotics (09615.HK) reported interim results for the six months ending June 30, 2026, with revenue of RMB 237.3 million, a 54.7% year-on-year increase. The company, which provides a standardized 'brain-eye-hand' component platform for embodied intelligent robots, achieved a gross margin of 65.0%. Overseas revenue grew 68.3% to RMB 99.5 million, contributing to an 81.4% gross margin in that segment. The company's customer retention rate reached 93.9%, with retained revenue of RMB 223.0 million. Despite an adjusted net loss of RMB 52.5 million, this was significantly lower than its R&D expenditure of RMB 80.1 million. The company highlighted breakthroughs in its 'robot brain' for autonomous task completion, a new dexterous hand with a 2-million-cycle lifespan, and advanced 3D vision tracking. A securities analyst noted that by positioning as a cross-form component supplier, Mech-Mind avoids direct competition with robot body manufacturers and benefits from industry-wide growth. A CIC industry report cited forecasts the global AI+3D vision-guided intelligent robot component market to grow from ~RMB 1.8 billion in 2025 to RMB 10.6 billion by 2030, with potential to exceed RMB 100 billion by 2035.
Read sourceMech-Mind Robotics Posts First Half-Year Report After IPO, Orders and Revenue Surge
Mech-Mind Robotics (09615.HK) released its first interim results since listing on the Hong Kong Stock Exchange on September 1. For the first half of 2026, revenue reached RMB 237.3 million, up 54.7% year-on-year, while gross profit rose 63.6% to RMB 154.2 million, with gross margin improving from 61.4% to 65.0%. New orders surged 75.3% to RMB 335.4 million, indicating strong demand. The company's AI detection and measurement business grew 128.4% to RMB 21.1 million. Customer retention remained high at 93.9%, with over 30,000 units deployed globally, including at 100+ Fortune 500 firms. Despite a 72.9% increase in R&D spending to RMB 80.1 million, the adjusted net loss narrowed to RMB 52.5 million from RMB 55.8 million. Overseas revenue accounted for 41.9% of total revenue, with 86.5% from Europe, the US, Japan, and South Korea. Management emphasized that the company's growth is driven by intelligent software ('brain, eyes, hands') rather than robot form factors, and that all revenue comes from real customer deployments. The company holds a 22.1% global market share in AI+3D vision-guided non-specialized robot components, according to a Frost & Sullivan report.
Read sourceMech-Mind Robotics (09615) IPO Sees 3835x Oversubscription, Trades 20% Below Issue Price
Mech-Mind Robotics, an AI-powered robot component supplier, debuted on the Hong Kong Stock Exchange on September 1, 2026, at an issue price of HKD 101.7. The IPO was massively oversubscribed by 3,835 times with 252,500 applicants, setting a 2026 record for robotics IPOs in Hong Kong. Nine cornerstone investors, led by Baillie Gifford, subscribed to 62.02% of the global offering. Despite the strong demand, the stock fell 1.87% on its first day and continued to decline, reaching a low of HKD 75.4 on September 4. By September 21, the stock was trading at HKD 80.3, a 20% discount from the issue price. The article analyzes the company's fundamentals, noting high revenue growth (46.6% CAGR from 2023-2025) and gross margins (64.6%), but persistent net losses totaling over 1 billion yuan over three years. It highlights the company's leading 22.1% global market share in AI+3D vision-guided robot components and its expansion into overseas markets, which yield higher margins. The analysis concludes that while the company is well-positioned in a high-growth market with low penetration, its high valuation (over 30x price-to-sales) requires continued rapid revenue growth and narrowing losses to be justified.
Read sourceShow 2 older updatesHide older updates
Mech-Mind Robotics (09615) IPO Sees 3,835x Oversubscription, Shares Trade 20% Below Issue Price
Mech-Mind Robotics (09615), a provider of AI-powered 3D vision and intelligent components for robots, debuted on the Hong Kong Stock Exchange on September 1, 2026, at an issue price of HKD 101.7. The IPO saw a record 3,835x oversubscription in its Hong Kong public offering, with 252,500 applicants and nine cornerstone investors subscribing for 62.02% of the global offering. Despite the strong demand, the stock fell 1.87% on its first day and continued to decline, reaching a low of HKD 75.4 on September 4. By September 21, the stock traded at HKD 80.3, a 20% discount from the issue price. The article analyzes the company's financials, noting high revenue growth (46.6% CAGR from 2023 to 2025) and gross margins (64.6% in 2025), but persistent net losses totaling RMB 1.044 billion over three years. It highlights the company's global market leadership with a 22.1% revenue share in AI+3D vision-guided robot components, its overseas expansion (50.3% of revenue from abroad with 79.2% gross margin), and the long-term potential of the low-penetration market. However, it cautions that the high valuation (over 30x price-to-sales) requires sustained revenue growth and narrowing losses to justify the premium.
Mech-Mind Robotics Reports 54.7% Revenue Growth in First Post-IPO Half-Year Results
Mech-Mind Robotics (09615.HK), which listed on the Hong Kong Stock Exchange on September 1, 2026, released its first interim results as a public company on September 24. For the first half of 2026, the company reported revenue of RMB 237.3 million, a 54.7% year-on-year increase. Gross profit rose 63.6% to RMB 154.2 million, with gross margin improving from 61.4% to 65.0%. New orders surged 75.3% to RMB 335.4 million, outpacing revenue growth and indicating strong future visibility. The company's AI-driven inspection and measurement business saw revenue jump 128.4% to RMB 21.1 million. Customer retention remained high with a 93.9% repurchase rate. Overseas revenue accounted for 41.9% of total revenue, with 86.5% from Europe, the US, Japan, and South Korea. Despite a 72.9% increase in R&D spending to RMB 80.1 million, the adjusted net loss narrowed to RMB 52.5 million from RMB 55.8 million. The company attributed the loss to strategic, high-intensity R&D investment. Founder and CEO Shao Tianlan stated the company will maintain a principle of not exaggerating or falsifying, reporting progress and challenges with solid products and plain language. The article positions the results as evidence of a shift in the embodied intelligence sector from concept-driven valuation to value based on intelligence and commercial delivery.
Read source