France’s 5-Year CDS Spread Hits 45 Bps, Highest Since March 2020
France’s 5-year credit default swap (CDS) spread has risen above 45 basis points, the highest level since March 2020, according to LSEG data. The increase reflects heightened market concern over France’s fiscal and political stability, with some reports citing ongoing political uncertainty and budget deficit worries. The CDS spread had previously reached 41.5 bps on September 18, before climbing further.
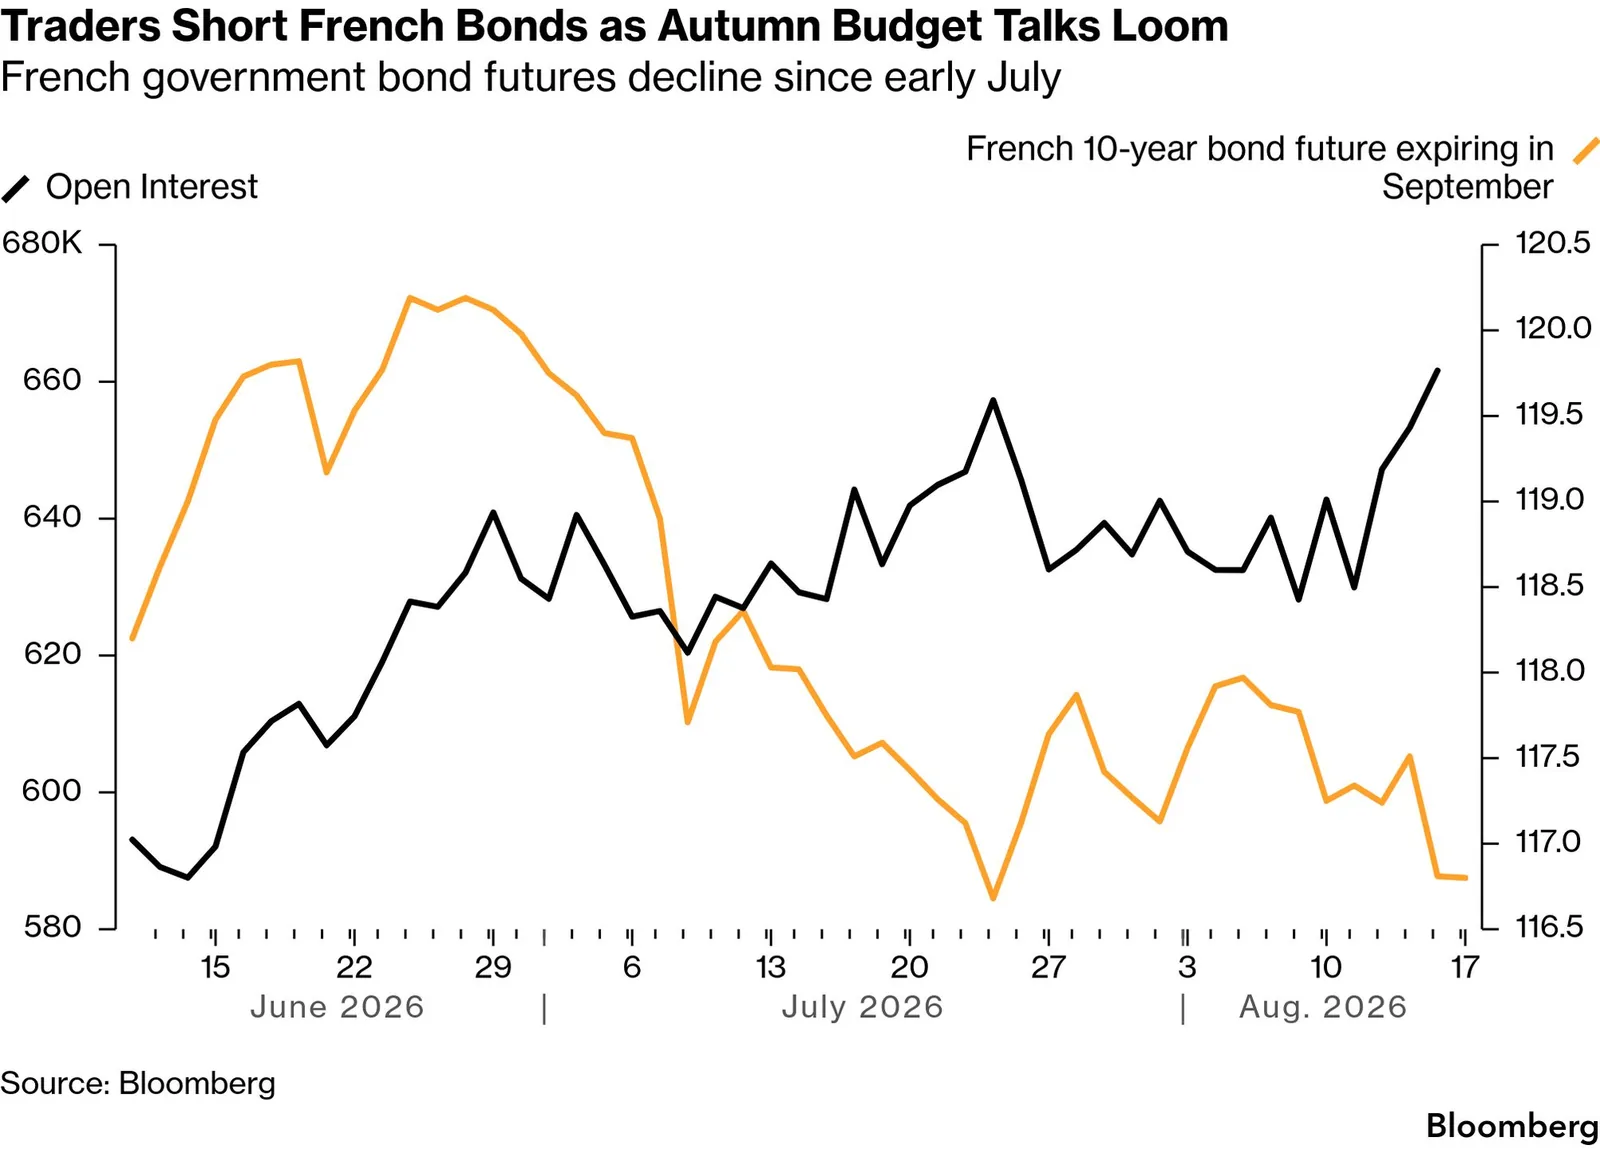 Reference image
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Common ground
- French CDS at 41.5 basis points is not a crisis, but it is a warning signal worth paying attention to.
- The move from 12 bps in 2021 to 41 bps is partly a return to normal levels after ECB policies artificially lowered spreads.
- France's political gridlock and repeated budget misses are real concerns that markets are pricing in.
- The bond spread between French and German debt is a more important metric to watch than CDS alone.
- The ECB's Transmission Protection Instrument provides a credible backstop against a full-blown crisis.
Points of contention
- One side sees the CDS rise as a symptom of deep democratic dysfunction, while the other sees it as a normal fiscal adjustment with political noise.
- There is disagreement on whether the trend from 12 to 41 bps is a dangerous deterioration or a healthy normalization from an artificial low.
- The use of Article 49.3 is viewed as a democratic bypass by one side and a long-standing constitutional feature by the other.
- One side argues the ECB safety net is strong enough to contain the risk, while the other warns it won't work if political problems get worse.
Blind spots
- Both sides may be underestimating how political gridlock in France could weaken the entire European Union's credibility over time.
- The discussion focuses on current numbers but doesn't fully explore what happens if the bond spread to Germany keeps rising toward 150 bps.
- Neither side deeply examines how public anger over pension reforms and spending cuts could fuel more instability in the next election.
WorldAttention’s read
French CDS at 41.5 basis points is not a crisis, but it is a real warning. The rise from 12 bps in 2021 is partly a return to normal after ECB policies, but it also reflects growing worries about France's political gridlock and repeated budget misses. One side argues this is just a fiscal headache with a safety net in place, while the other sees it as a symptom of democratic dysfunction that could get worse. Both agree the bond spread to Germany is the key number to watch. The real blind spot is how France's political troubles could slowly erode trust in the entire European project, especially if the next election brings more instability. For now, this is a yellow flag, not a red one, but ignoring the trend could turn a manageable problem into a serious one.
Reporting timeline
France's 5-Year CDS Spread Hits 45 Bps, Highest Since March 2020
According to LSEG data reported by 财联社 on September 21, the spread on France's 5-year credit default swaps (CDS) has broken through 45 basis points, reaching its highest level since March 2020. This increase in the CDS spread indicates a rise in perceived credit risk for French sovereign debt, reflecting heightened market concerns about France's fiscal and economic outlook. The level marks a significant milestone, surpassing previous post-pandemic highs and signaling renewed stress in European bond markets. The data point is attributed to LSEG (London Stock Exchange Group) and was published by Chinese financial media outlet 财联社. No further context or commentary was provided in the brief report.
France's 5-Year Credit Default Swap Spread Hits Highest Since March 2020
Data from financial information provider Jin10 shows that France's 5-year credit default swap (CDS) spread has risen above 45 basis points, reaching its highest level since March 2020. This increase in the cost of insuring French sovereign debt against default reflects growing market concern about the country's fiscal and political stability. The previous peak in March 2020 occurred during the initial global market turmoil caused by the COVID-19 pandemic. The current rise comes amid ongoing political uncertainty in France following recent elections and concerns over the government's budget deficit and debt levels. The CDS spread is a key indicator of perceived credit risk, and the breach of the 45 basis point threshold signals heightened investor anxiety about France's economic outlook.
Read sourceFrance's 5-Year Credit Default Swap Surges to Highest Level Since April 2025
According to a report from tradealpha, France's 5-year credit default swap (CDS) has surged to 41.5 basis points. This level marks the highest point since April 2025, indicating a significant increase in the perceived risk of a French sovereign debt default. The rise in CDS spreads reflects growing market concern over France's fiscal and economic outlook.
Show 2 older updatesHide older updates
France's Five-Year CDS Spread Hits 41.5 Bps, Highest Since April 2025
On September 18, France's five-year credit default swap (CDS) spread surged to 41.5 basis points, marking the highest level since April 2025, according to Cailian Press. The increase in the CDS spread indicates a rise in perceived credit risk for French sovereign debt, reflecting heightened market concerns about the country's fiscal or political stability. The report does not specify the cause of the surge, but the level represents a notable increase from recent months, suggesting growing investor caution regarding French bonds.
Read sourceFrance's 5-Year Credit Default Swap Surges to 41.5 Basis Points, Highest Since April 2025
According to data from financial information provider Jin10, France's 5-year credit default swap (CDS) has surged to 41.5 basis points. This level marks the highest point for the instrument since April 2025. The increase in the CDS spread indicates a rise in the perceived risk of a French sovereign debt default, reflecting growing market concerns about the country's fiscal health or political stability. The report does not attribute the move to any specific event or provide further context, but the data point itself signals a notable shift in investor sentiment toward French government bonds.
Read source