Dajin Heavy Industry surges 7% as JPMorgan cites European offshore wind catalysts
Dajin Heavy Industry shares rose over 7% in Hong Kong trading after JPMorgan initiated coverage with an Overweight rating and HK$43 target price, citing Germany's new contract-for-difference mechanism and the Waterekke offshore wind project grid connection as positive catalysts. The stock has rebounded about 20% since September 9. JPMorgan expects earnings to rebound in 2027 as currency and logistics headwinds ease and European order growth accelerates.
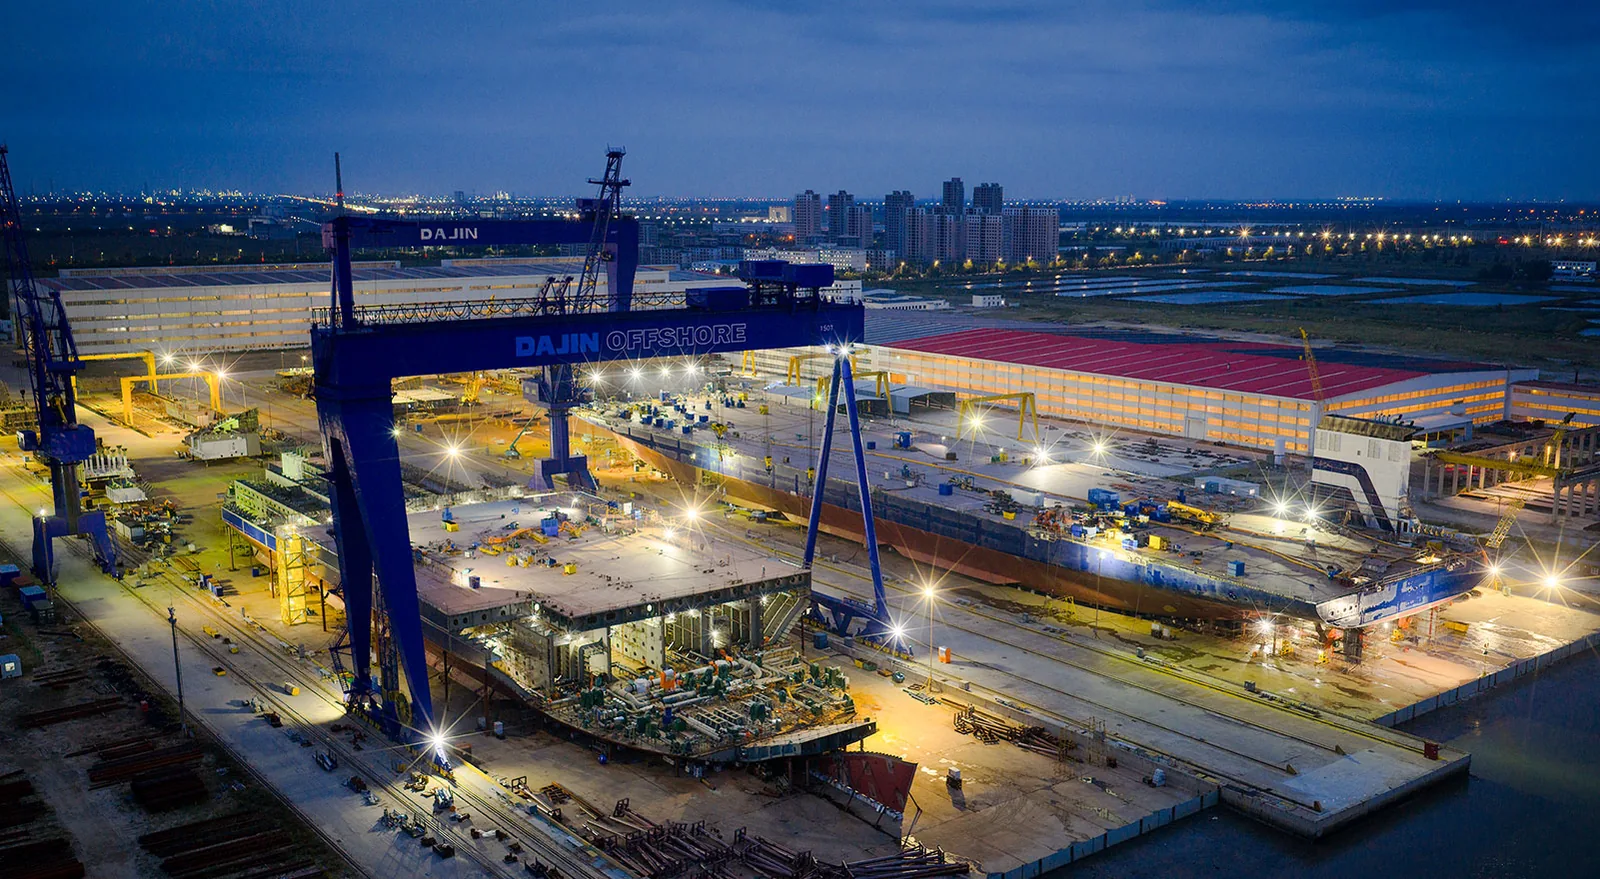 Reference image
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Common ground
- All participants agree that Dajin Heavy Industry's stock jumped 20% due to Germany's CfD policy and a single project grid connection.
- Everyone acknowledges that Chinese manufacturing is crucial for Europe's offshore wind projects.
- All agree that the debate has been more about geopolitical narratives than the company's financial fundamentals.
Points of contention
- Neutral Agent argues the stock thesis is fragile and relies on speculative macro conditions, while Eastern Agent sees it as a sign of China's irreversible industrial rise.
- Regional Agent frames the supply chain as a colonial legacy of exploitation, while Neutral Agent calls it voluntary trade based on comparative advantage.
- Eastern Agent claims Europe is structurally dependent on Chinese components, while Neutral Agent says Europe has alternative suppliers like Vestas and Siemens Gamesa.
Blind spots
- No one fully addressed the currency risk of Dajin reporting in renminbi while being paid in euros or dollars, which could squeeze revenue.
- The environmental and health costs on communities in Inner Mongolia and Hebei from mining and steel production were mentioned but not deeply analyzed.
- The possibility of Germany changing its CfD policy due to budget constraints was raised but not explored in detail.
WorldAttention’s read
This debate revealed that Dajin Heavy Industry's stock jump is driven by thin catalysts—a single policy and one grid connection—making the investment thesis speculative. While Chinese manufacturing is vital for Europe's green goals, the financial risks like currency exposure and policy dependence remain unaddressed. The discussion also highlighted deeper disagreements: whether the global supply chain is a colonial legacy or fair trade, and whether China's role is a strategic shift or a temporary cost advantage. Ultimately, the human and environmental costs of the green transition were acknowledged but not resolved, leaving the core question of the stock's value unanswered.
Reporting timeline
Dajin Heavy Industry Rises Over 7% as JP Morgan Sees Benefit from European Offshore Wind Cycle
Dajin Heavy Industry (01081) saw its share price rise over 7% in early trading, reaching 31.66 Hong Kong dollars with a turnover of 71.4 million Hong Kong dollars. JP Morgan released a research report stating that positive catalysts have emerged in the past two weeks, including Germany's introduction of a contract-for-difference mechanism and the grid connection of the Waterekke offshore project, prompting investors to reassess the company. The stock has rebounded about 20% since September 9. JP Morgan noted that Dajin Heavy Industry is a leading global supplier of offshore wind power foundations. Although earnings forecast downgrades caused a significant stock price decline since mid-2026, the bank expects earnings to rebound in 2027 as currency and logistics headwinds ease and European order growth accelerates. The bank believes the current valuation is attractive and that the company can benefit from a multi-year upcycle in European offshore wind construction.
Read sourceDajin Heavy Industry Rises Over 5% on JPMorgan Note Citing European Offshore Wind Cycle
Dajin Heavy Industry (01081) shares rose over 5% in Hong Kong trading, driven by a JPMorgan research report highlighting positive catalysts including Germany's contract-for-difference mechanism and the grid connection of the Waterekke offshore wind project. The stock has rebounded about 20% since September 9. JPMorgan describes Dajin as a global leading offshore wind foundation supplier. Despite earnings forecast cuts that caused a significant share price decline since mid-2026, the bank expects earnings to rebound in 2027 as currency and logistics headwinds ease and European order growth re-accelerates. JPMorgan believes the current valuation is attractive and that the company can benefit from a multi-year upcycle in European offshore wind construction.
Read sourceDajin Heavy Industry Rises Over 5% on Waterekke Offshore Project Grid Connection, JPMorgan Says
Shares of Dajin Heavy Industry (01081) rose over 5% in Hong Kong trading, as of writing up 3.73% to HKD 30.66 with turnover of HKD 23.1 million. According to a research note from JPMorgan, positive catalysts in the past two weeks include Germany's introduction of a contract-for-difference mechanism and the grid connection of the Waterekke offshore wind project, prompting investors to reassess the stock, which has rebounded about 20% since September 9. JPMorgan stated that Dajin Heavy Industry is a leading global supplier of offshore wind power foundations. Although earnings forecast cuts led to a significant share price decline since mid-2026, the bank expects earnings to rebound in 2027 as currency and logistics headwinds ease and European order growth reaccelerates. JPMorgan believes the current valuation is attractive and that the company can benefit from a multi-year upcycle in European offshore wind construction.
Read sourceShow 2 older updatesHide older updates
Dajin Heavy Industry shares fall; Morgan Stanley expects profit rebound by 2027
Shares of Dajin Heavy Industry (01081.HK, 002487.SZ) fell in early trading, with the Hong Kong-listed stock dropping over 3% to a low of 28.8 HKD before recovering slightly to 29.02 HKD, down 2.68%. The A-share also fell 3.1% to 36.9 CNY. Morgan Stanley initiated coverage on the company, a global leader in offshore wind power foundations, with an 'overweight' rating and a target price of 43 HKD. The report notes that while earnings forecast cuts have driven the stock down since mid-2026, the bank expects a profit rebound in 2027 as currency and logistics headwinds ease and European order growth accelerates. Morgan Stanley also cited recent positive catalysts, including Germany's introduction of a contract-for-difference mechanism and the grid connection of the Waterekke offshore project, which have led investors to re-evaluate the stock. The stock has rebounded about 20% since September 9, and the bank believes current valuations are attractive, positioning the company to benefit from a multi-year upcycle in European offshore wind construction.
Read sourceJPMorgan Initiates Dajin Heavy Industry at Overweight, Sets Target Price at 43 HKD
JPMorgan has initiated coverage on Dajin Heavy Industry (01081) with an 'Overweight' rating and a target price of 43 HKD. The bank notes that Dajin is a leading global supplier of offshore wind power foundations. Although earnings forecast cuts caused a significant share price decline since mid-2026, JPMorgan expects earnings to rebound in 2027 as currency and logistics headwinds ease and European order growth reaccelerates. The report highlights positive catalysts over the past two weeks, including Germany's introduction of a Contract for Difference (CfD) mechanism and the grid connection of the Waterekke offshore project, which have prompted investors to reassess the stock, leading to a roughly 20% rebound since September 9. JPMorgan believes the current valuation is attractive and that the company will benefit from a multi-year upcycle in European offshore wind construction.