Chongqing Brewery Pressured by Investors Over Slowing Growth, Underperformance vs. Yanjing U8
Chongqing Brewery (600132.SH) reported a 2.98% revenue decline to 8.576 billion yuan and a 7.98% net profit drop in H1 2024, making it the only major Chinese brewer with falling revenue and profit. During a September 23 investor briefing, executives cited weak on-premise consumption and bad weather, but investors focused on internal issues: a 7.48% revenue drop in the core Sichuan-Chongqing market, rising sales expenses to 16.4% of revenue (highest among peers), and sluggish growth of flagship brand Wusu versus rival Yanjing U8. Management did not directly answer questions about Wusu's strategy.
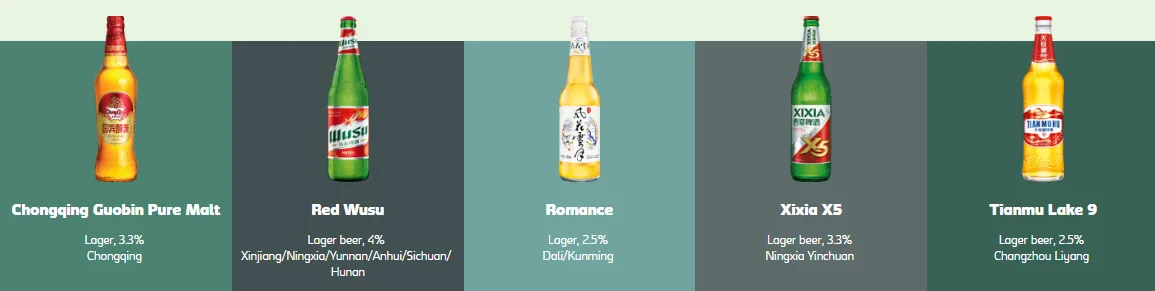 Reference image
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Reporting timeline
Chongqing Brewery faces investor pressure over weak sales and U8 competition
Chongqing Brewery (600132.SH) reported a 2.98% revenue decline to 85.76 billion yuan and a 7.98% drop in net profit for the first half of 2024, making it the only major Chinese brewer with falling revenue and profit. During a September 23 investor meeting, executives attributed the decline to weak on-premise consumption, a slower-than-expected recovery, and bad weather. Investors pressed management on internal issues, including declining advertising efficiency, pressure in the core Sichuan-Chongqing market (where regional revenue fell 7.48%), and the sluggish growth of the flagship Wusu brand compared to rival Yanjing's U8. The company's sales expenses rose 5.23% to 14.03 billion yuan, with the expense ratio reaching 16.4%, the highest among five listed brewers. Management did not directly answer questions about Wusu's growth strategy but cited marketing initiatives. Chongqing Brewery launched 49 new products in the half, including craft beer and non-beer beverages, though their sales impact remains undisclosed.
Read sourceChongqing Brewery Pressured at Home Base, Investors Question Why It Can't Beat Yanjing U8
Chongqing Brewery (600132.SH) faced tough questions from investors during a September 23 performance briefing, as it was the only one among China's top five domestic brewers to report declines in both revenue and profit in the first half of 2024. Revenue fell 2.98% year-on-year to 8.576 billion yuan, while net profit attributable to shareholders dropped 7.98% to 796 million yuan. CFO Chin Wee Hua attributed the results to weak on-premise consumption channels, a slower-than-expected economic recovery, and adverse weather. However, investors focused on internal issues, including declining advertising efficiency, pressure in the core Sichuan-Chongqing-Guizhou region (where revenue fell 7.48%), and sluggish growth of the flagship Wusu brand. Wusu's national growth rate was compared unfavorably to Yanjing's U8, which has surged from 100,000 kiloliters to about 900,000 kiloliters in five years. Management did not directly answer questions about Wusu's revival but listed marketing initiatives. The company's sales expense ratio rose to 16.4%, the highest among the five peers, as advertising spending increased 9.7% without driving proportional sales growth. Chongqing Brewery launched 49 new products in the half, including craft beer and non-beer categories, but has not disclosed their performance.
Chongqing Brewery Faces Investor Pressure Over Weak Performance vs. Yanjing U8
Chongqing Brewery (600132.SH) faced tough questions from investors during a September 23 performance briefing, as it was the only one among China's top five domestic beer companies to report declines in both revenue and net profit for the first half of 2024. Revenue fell 2.98% year-on-year to 8.576 billion yuan, while net profit attributable to shareholders dropped 7.98% to 796 million yuan. CFO Chin Wee Hua attributed the results to a weak on-premise consumption channel, a slower-than-expected economic recovery, and adverse weather. However, investors focused on internal issues, including declining advertising efficiency, pressure in the core Sichuan-Chongqing market, and sluggish growth of the flagship Wusu brand. Revenue in the central region, which accounts for about 40% of total sales, fell 7.48%. The company's sales expense ratio rose to 16.4%, the highest among the five major brewers, as advertising costs increased 9.7% without driving proportional sales growth. Investors specifically questioned why Wusu's national growth rate lagged far behind Yanjing's U8 brand. Management did not directly answer but listed marketing initiatives for Wusu. The company launched 49 new products in the half, including craft beer and non-beer beverages, but has not disclosed their sales contributions.
Read sourceShow 2 older updatesHide older updates
Chongqing Brewery Only Major Brewer with Revenue and Profit Decline in First Half
According to an analysis by Sina Finance, China's beer industry is undergoing a significant shake-up amid stagnant overall consumption. In the first half of 2026, total revenue for eight listed brewers was 656.06 billion yuan, down 0.1% year-on-year, while net profit fell 2.63%. Chongqing Brewery was the only major brewer to report declines in both revenue (down 2.98% to 85.76 billion yuan) and net profit (down 7.98% to 7.96 billion yuan). The analysis attributes the company's struggles to a dual decline in sales volume and price per kiloliter, particularly in its high-end (8 yuan+) and mainstream (4-8 yuan) product segments. Key brands like Wusu and 1664 Blanc are underperforming. The report notes that cost advantages from raw materials are diminishing, while the company increased sales expenses by 5.23%, further pressuring margins. The analysis also highlights Chongqing Brewery's high debt-to-asset ratio of 71.88%, well above the industry average, primarily due to payables to suppliers.
Read sourceChongqing Brewery Pressured by Investors Over Slowing Growth, Underperformance vs. Yanjing U8
On September 23, Chongqing Brewery (600132.SH) participated in a collective investor reception day and semi-annual performance briefing for listed companies in the Chongqing region. According to a review by International Financial News, among five major domestic beer companies, Chongqing Brewery was the only one to see both revenue and net profit decline in the first half of the year. Revenue fell 2.98% year-on-year to 8.576 billion yuan, while net profit attributable to shareholders dropped 7.98% to 796 million yuan. CFO Chin Wee Hua attributed the decline to weak on-premise consumption channels, a slower-than-expected consumption recovery, and adverse weather. Investors focused on internal issues such as declining advertising efficiency, pressure in the core Sichuan-Chongqing market, and weak growth of the flagship Wusu brand. Revenue in the central region (Sichuan, Chongqing, Guizhou), which accounts for about 40% of total revenue, fell 7.48%. Competitors like China Resources, Tsingtao, and Yanjing have intensified competition in the southwest. Sales expenses rose 5.23% to 1.403 billion yuan, with the sales expense ratio reaching 16.4%, the highest among the five domestic brewers. Management stated they will maintain reasonable expense levels. Investors questioned why Wusu's growth lags far behind Yanjing U8 and asked for measures to revive growth. Management did not directly answer but listed marketing activities for Wusu. The company launched 49 new products in the first half, including craft beer, low-alcohol beer, and non-beer beverages, but has not disclosed their sales performance.
Read source