Bosideng achieves double-digit retail growth; analysts maintain Buy ratings ahead of peak season
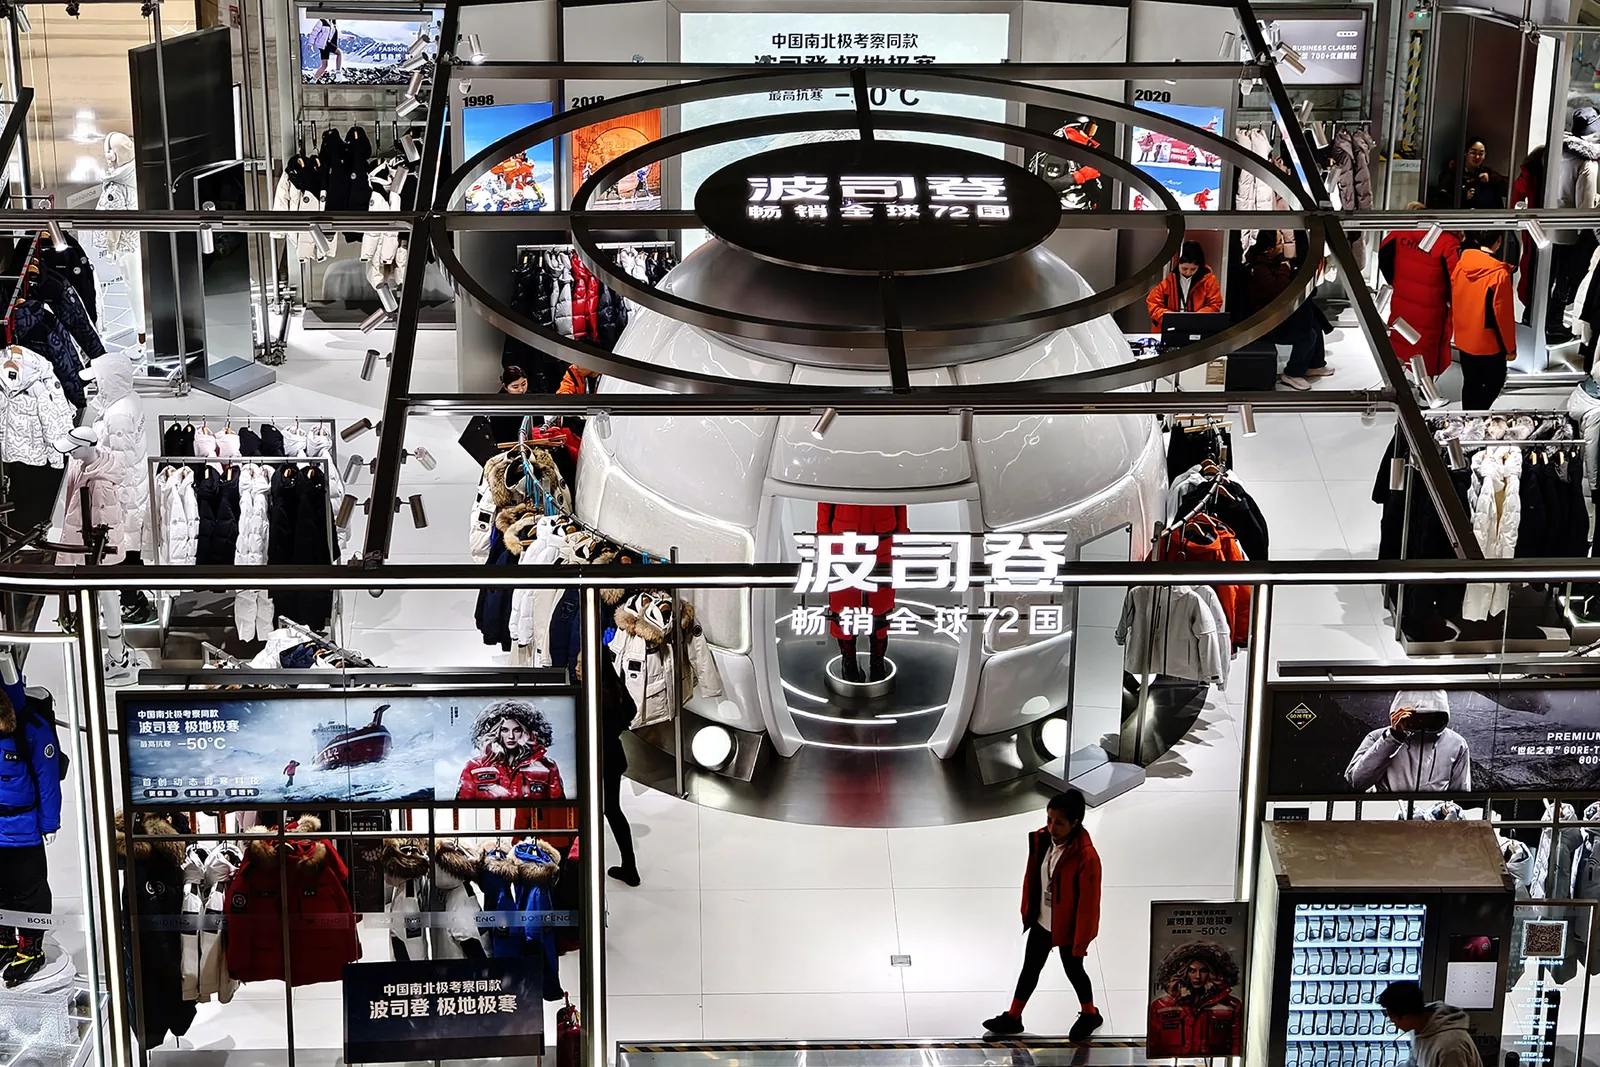
Chinese down jacket maker Bosideng (3998.HK) reported double-digit retail growth for its main brand from April to August 2026, with online and direct-store channels outperforming wholesale. Analysts from CICC, Zheshang Securities, and Huatai Securities maintained Buy or Outperform ratings. CICC forecasts FY27 net profit of 4.3 billion yuan and FY28 net profit of 4.6 billion yuan. The company repurchased 13 million shares from September 21-23 and expanded its high-end VERTEX store network, including a new Shanghai location.
 Illustration
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Reporting timeline
Bosideng (3998.HK) Sees Robust Retail Growth Ahead of Peak Season, Analysts Maintain Buy Ratings
As autumn weather cools and winter consumption approaches, Chinese down jacket maker Bosideng (3998.HK) is attracting market attention ahead of promotional events like Singles' Day. Analysts from CICC, Zheshang Securities, and Huatai Securities have maintained 'Buy' or 'Outperform' ratings on the stock. CICC forecasts net profit of 4.3 billion yuan for FY27 and 4.6 billion yuan for FY28. The company has been actively repurchasing shares, buying back 13 million shares from September 21-23. Key operational signals include double-digit retail growth for the main brand from April to August, with proactive adjustment of delivery pace for healthy inventory. Online and direct-operated channels are outperforming wholesale channels. The company is optimizing its product structure by introducing new series like Bosideng AREAL, designed by Kim Jones, and focusing on four core categories. Analysts highlight strategic upgrades in product, channel, and supply chain to reduce seasonal dependency and elevate the brand towards an international fashion-tech functional apparel group. CICC has a target price of 5.65 HKD, while Huatai targets 6.03 HKD.
Bosideng Retail Growth Strong Ahead of Peak Season; Analysts Maintain Buy Ratings
Chinese down jacket maker Bosideng (3998.HK) is showing positive retail momentum as autumn begins, with analysts from CICC, Zheshang Securities, and Huatai Securities maintaining 'buy' or 'outperform' ratings. CICC forecasts FY27 and FY28 net profit at 4.3 billion yuan and 4.6 billion yuan respectively, while Zheshang expects FY27-FY29 net profit of 4.32 billion, 4.64 billion, and 4.97 billion yuan. Key operational signals include double-digit retail growth for the main brand from April to August, active adjustment of shipment pace to ensure healthy inventory, strong online and direct-store channel performance, and product mix optimization with new series like AREAL. The company is expanding into higher-end products and store formats, including the AREAL line designed by Kim Jones and VERTEX flagship stores, aiming to reduce seasonal dependency and elevate brand positioning. Bosideng has also been actively repurchasing shares, buying back 13 million shares from September 21 to 23. CICC maintains a target price of 5.65 HKD, while Huatai targets 6.03 HKD.
Read sourceCICC Says Bosideng 1HFY27 Retail Shows High-Quality Growth, Maintains Outperform Rating
A research report from China International Capital Corporation (CICC) indicates that Bosideng (03998.HK) demonstrated positive and healthy retail performance in the first half of fiscal year 2027 (1HFY27). CICC estimates that the main brand's terminal retail sales grew by a double-digit percentage year-on-year from April to August, showcasing strong operational resilience amid a complex and changing consumer environment. The report notes that online sales grew faster than offline, and direct sales outpaced distribution. Bosideng is optimizing its channel structure and store operations to enhance brand influence in high-tier cities and among younger consumers. CICC forecasts Bosideng Group's 1HFY27 revenue to be roughly flat year-on-year, with net profit slightly increasing due to strict cost control, meeting expectations. The report highlights Bosideng's strategic focus on controlling delivery pace, product innovation, and refined channel management. In July, Bosideng opened its first VERTEX store in East China at Shanghai's兴业太古汇, expanding its high-end channel network. Additionally, Kim Jones has again collaborated with Bosideng on the AREAL spring-summer 2026 collection. CICC maintains its 'Outperform' rating on the stock.
Read sourceShow 2 older updatesHide older updates
CICC Forecasts Bosideng's Double-Digit Retail Growth in 1HFY27, Maintains Outperform Rating
According to a CICC research report cited by Zhitong Finance, Bosideng (03998) is expected to achieve double-digit year-on-year growth in its main brand's terminal retail sales for the period of April to August 2026 (1HFY27). The report highlights that online channels are growing faster than offline, and direct sales are outpacing distribution. Bosideng's overall group revenue for 1HFY27 is forecast to be flat year-on-year, with a slight increase in net profit due to strict cost control. CICC maintains an 'Outperform' rating on the stock. The company is expanding its high-end VERTEX store network, with a new store in Shanghai, and has launched a new AREAL spring/summer collection in collaboration with Kim Jones. CICC views Bosideng's strategic focus on brand upgrading, product innovation, and channel optimization as key to its long-term competitiveness amid a challenging consumer environment.
Read sourceCICC Says Bosideng Retail Sales Steady in H1, Maintains Outperform Rating
CICC (China International Capital Corporation) released a research report indicating that after discussions with Bosideng management, the company's terminal retail sales continued to achieve steady growth in the first half of its fiscal year ending September 30. CICC attributes this to Bosideng's leading brand competitiveness. The group has proactively slowed its shipment pace to lay a solid foundation for healthy operations during the peak season. CICC estimates that from April to August, Bosideng's main brand terminal retail sales will record a double-digit year-on-year increase, with online retail turnover expected to grow by about 20% year-on-year, outperforming a mid-single-digit increase offline. Direct retail sales are expected to grow over 10% driven by same-store sales, better than a single-digit increase for the distribution channel. CICC maintains its earnings forecasts for fiscal years 2027 and 2028 at 4.3 billion and 4.6 billion yuan respectively, and keeps its 'Outperform' rating and target price of 5.65 Hong Kong dollars unchanged.