Auntea Jenny Shares Surge Over 14% on Strong H1 Profit, Dividend Hike to 66%
Shares of Chinese tea chain Auntea Jenny surged over 14% in Hong Kong trading after reporting strong first-half 2025 results. Revenue rose 42.4% year-on-year to 2.589 billion yuan, net profit jumped 58.3% to 321 million yuan, and the company increased its dividend payout ratio to 66%. The company's global store count reached 13,155, with rapid expansion in lower-tier cities. Six shareholders also issued voluntary lock-up commitments through November 7.
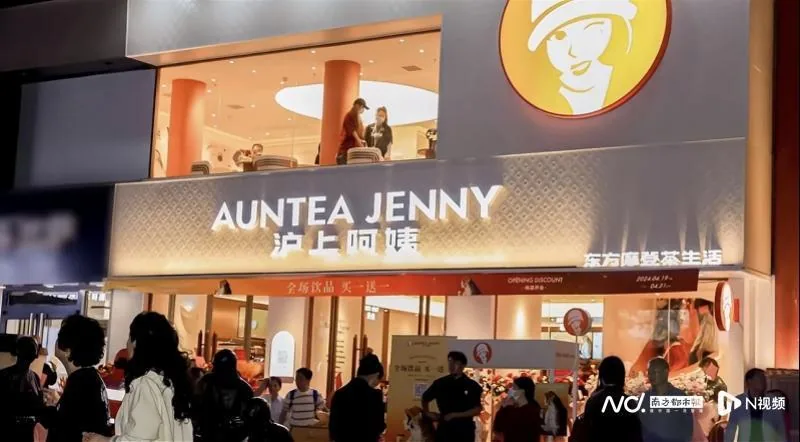 Reference image
Editorial responsibility
- No named human review is recorded for this page.
- Reports are grouped by semantic similarity and deterministic rules. Language models may assist titles, summaries, translation and cross-source analysis; the page reads the event directly, while its address stays stable when the title changes.
- Summary covers the current reports
Cross-source coverage
Reporting timeline
Guohai Securities Initiates Coverage on Auntea Jenny with Buy Rating, Cites Expansion in Lower-Tier Cities
Guohai Securities has initiated coverage on Auntea Jenny (stock code: 02589) with a 'Buy' rating, citing the company's rapid store expansion and deepening penetration in lower-tier cities. The brokerage highlighted the company's first-half 2026 results, which showed revenue of 2.589 billion yuan, up 42.4% year-on-year, and net profit attributable to shareholders of 321 million yuan, up 58.3%. The total global store count reached 13,155, with 53.4% located in third-tier and below cities. Guohai Securities noted stable profitability with a gross margin of 31.6% and an adjusted net margin of 13.33%. The firm forecasts 2026-2028 revenue of 5.41, 6.15, and 6.77 billion yuan respectively, and adjusted net profit of 680, 770, and 850 million yuan. The rating is based on expectations of continued brand expansion, product innovation, and membership operations driving single-store performance, as well as the scaling of its franchise network and supply chain. Risks include slower-than-expected store openings, weaker same-store sales, intensified competition, rising raw material costs, and food safety issues.
Guohai Securities Initiates Coverage on Auntea Jenny with Buy Rating, Citing Expansion in Lower-Tier Cities
Guohai Securities has initiated coverage on Auntea Jenny (02589) with a 'Buy' rating, highlighting strong growth driven by rapid store expansion in lower-tier cities. The company reported first-half 2026 revenue of 2.589 billion yuan, up 42.4% year-on-year, and net profit of 321 million yuan, up 58.3%. Its global store count reached 13,155, with 53.4% located in third-tier and below cities. The brokerage forecasts 2026-2028 revenue of 5.41, 6.15, and 6.77 billion yuan respectively, and adjusted net profit of 680, 770, and 850 million yuan. Guohai Securities expects continued growth from brand expansion, product innovation, membership operations, and supply chain scale effects. Risks include slower store openings, weaker same-store sales, intensified competition, rising raw material costs, and food safety issues.
Guohai Securities Initiates Coverage on Auntea Jenny with Buy Rating, Citing Expansion in Lower-Tier Cities
Guohai Securities has initiated coverage on Auntea Jenny (stock code 02589) with a 'Buy' rating, according to a research report summarized by Jinwu Finance. The brokerage highlighted the company's strong first-half 2026 performance, with revenue reaching 2.589 billion yuan, a 42.4% year-on-year increase, and net profit attributable to shareholders rising 58.3% to 321 million yuan. The report emphasizes rapid store expansion, particularly in lower-tier cities, where stores in third-tier and below accounted for 53.4% of the total 13,155 global stores as of mid-2026. This expansion drove growth in franchise-related revenue. Guohai Securities notes stable profitability with a 31.6% gross margin and a 13.33% adjusted net margin. The company's product innovation, including 142 new products under its 'Daily Health+' strategy, and a growing membership base with a 42.3% quarterly repurchase rate are seen as positive factors. Guohai Securities forecasts 2026-2028 revenue of 5.41, 6.15, and 6.77 billion yuan respectively, with adjusted net profit of 680, 770, and 850 million yuan. The 'Buy' rating is based on expectations of continued brand expansion, product innovation, and supply chain scale effects, though risks include slower store openings, weaker same-store sales, and industry competition.
Show 2 older updatesHide older updates
Auntea Jenny Shares Surge Over 16% on Strong H1 Profit, Dividend Hike
Shares of Auntea Jenny (02589) surged over 16% intraday, closing up 12.29% at HK$79.55 with a turnover of HK$56.89 million. The company reported strong first-half results: revenue of RMB 2.589 billion, up 42.4% year-on-year; gross profit of RMB 818 million, up 43.2%; net profit of RMB 321 million, up 58.3%; and adjusted net profit of RMB 345 million, up 41.6%. The company also increased its dividend payout ratio to 66%, rewarding shareholders generously. Auntea Jenny maintained rapid store expansion, with total stores reaching 13,155, a net increase of 3,719 year-on-year and 1,706 since the end of 2025. Additionally, last month, six shareholders issued voluntary lock-up commitments extending from August 7 to November 7, citing confidence in the company's operations and long-term growth prospects in the consumer sector.
Read sourceAuntea Jenny Shares Surge Over 14% on Strong First-Half Earnings and Generous Shareholder Returns
Shares of Auntea Jenny (stock code 02589) surged over 14% in Hong Kong trading, reaching 80.2 Hong Kong dollars with a turnover of 47.03 million Hong Kong dollars. The rally followed the company's announcement of strong first-half 2025 financial results, with revenue rising 42.4% year-on-year to 2.589 billion yuan, gross profit up 43.2% to 818 million yuan, and net profit surging 58.3% to 321 million yuan. Adjusted net profit increased 41.6% to 345 million yuan. The company also boosted its dividend payout ratio to 66%, signaling generous shareholder returns. Auntea Jenny maintained a rapid store expansion pace, with total store count reaching 13,155, a net increase of 3,719 year-on-year and 1,706 since the end of 2024. Additionally, in the previous month, six shareholders issued voluntary lock-up commitments extending from August 7 to November 7, citing confidence in the company's operational strength, mature systems, management team, and long-term growth prospects in the consumer sector.